
Buying a Home Today
Navigating the High Costs and Personal Aspirations in 2025
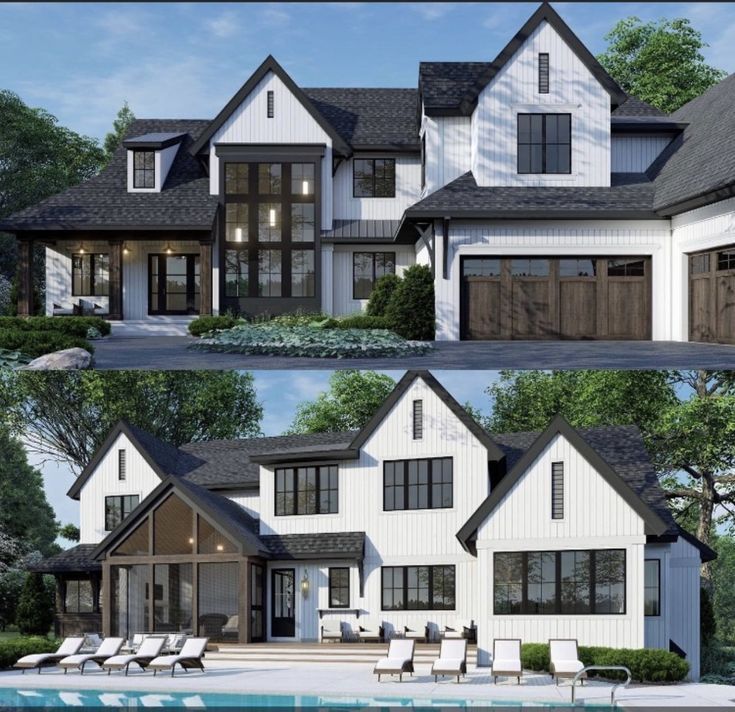
Key Highlights
- Assess Your Financial Situation: Understand your current budget, savings, and long-term financial plan.
- Understand Market Conditions: Be aware of market trends, mortgage rates, and inventory levels.
- Plan for Long-Term Investment: Consider homeownership as an investment and a lifestyle choice that includes both benefits and responsibilities.
Comprehensive Analysis and Considerations
Buying a home is indeed one of the most significant financial and emotional commitments you will make. While it may seem expensive now due to high prices and other factors, there is a variety of reasons why many individuals decide to proceed with homeownership. Below, we explore the factors you should consider as you move forward with your decision in today’s market conditions, and offer insights tailored to help you navigate this exciting transition.
Market Conditions and Trends
Home Prices and Inventory
The current housing market in 2025 continues to witness upward pressure on home prices. Even though there may be a slight deceleration in price growth, with experts anticipating average annual increases of around 2-3%, prices remain high. Inventory levels have shown some signs of balance, with reports suggesting a 3.5-month supply in areas that were previously under-stocked. However, a balanced market typically requires around 5 to 6 months of housing supply, and shortages in some regions can drive up competition.
Mortgage Rates
Mortgage rates in 2025 have generally stabilized around 6.5%. Although some predictions lean towards slight declines, it appears that rates are unlikely to fall drastically below 6% in the near term. As a buyer, securing a favorable mortgage rate is crucial. You should consider getting pre-approved for a mortgage to understand your purchasing power and lock in a rate that aligns with your financial goals.
Economic Influences
Economic factors such as inflation, interest rates, and even political or trade-related issues remain influential in shaping the housing market. While the market is expected to see modest growth, a confluence of economic uncertainties could affect long-term home values. Being aware of these economic factors can help you make an informed decision on whether to buy now or wait. For you, if the need for a stable home environment outweighs these risks, the decision to buy remains a viable option.
Personal and Financial Considerations
Financial Readiness
One of the most critical aspects when buying a home is assessing your personal financial health. This includes understanding your current budget, having sufficient savings for a down payment and closing costs, and ensuring that your credit score is in good shape. Even though home prices are high, if your finances are robust and you can secure a competitive mortgage rate, buying a home can set you up for long-term wealth building through equity accumulation.
Assessing the Long-Term Investment
Homeownership is not just about acquiring a property; it also represents a strategic long-term investment. While buying at a peak market might carry short-term risks, over time, a well-maintained property in a desirable area can appreciate in value. In your case, the commitment to proceed despite the high cost suggests that you’re prepared for the long-term gains. Consider the tax benefits available to homeowners, including deductions on mortgage interest and property taxes, which can help mitigate some of the upfront expenses.
Weighing the Pros and Cons
To help frame your decision, it is beneficial to examine both the opportunities and responsibilities that come with buying a home:
- Pros:
- Equity Building: Over time, making mortgage payments increases your ownership stake, potentially yielding significant equity.
- Tax Benefits: Homeownership can provide tax deductions and other fiscal benefits.
- Stability: Owning a home offers a stable living environment and the freedom to modify your space as you see fit.
- Cons:
- High Entry Costs: The need for a substantial down payment, closing costs, and potential renovations can be daunting.
- Long-Term Commitment: Real estate is a relatively illiquid asset, meaning selling a property can take time if circumstances change.
- Maintenance Responsibilities: Upkeep and repair costs add to the ongoing financial obligations of homeownership.
Making the Decision: Practical Steps
Stay Informed and Seek Professional Guidance
One of the most prudent steps you can take is to remain well-informed about the local market trends and broader economic indicators. Engaging with real estate agents, mortgage brokers, and financial advisors will equip you with detailed insights tailored to your specific circumstances. They can guide you through the complexities of the buying process, from evaluating properties to finalizing financing options.
Pre-Approval and Financing Strategy
Before you proceed, secure pre-approval for a mortgage. This not only gives you a clear picture of your purchasing range but also strengthens your position as a serious buyer when you negotiate the deal. Working with a reputable lender can help you understand the various mortgage products available and select the one that best fits your long-term objectives.
Balancing Emotions and Practicality
Buying a home is as much an emotional decision as it is a financial one. It’s natural to feel excitement about making such a significant investment, especially if you’ve committed to the idea despite the high costs. Balance your enthusiasm with a careful review of your financial situation and the practical aspects of homeownership. Consider your long-term goals: if you plan to settle in one place for several years, the advantage of building equity might outweigh the immediate concerns of high market prices.
Detailed Comparative Analysis Table
| Aspect | Pros | Cons | Key Considerations |
|---|---|---|---|
| Home Prices | Potential for future equity growth | High initial cost; risk of slow appreciation if market cools | Analyze local market trends and long-term forecasts |
| Mortgage Rates | Stable around 6.5%; opportunity to lock in rates | Slightly higher than historic lows; limited chances of a significant drop | Focus on rate locking and negotiations with lenders |
| Financial Readiness | Building long-term wealth; tax incentives | High upfront costs; ongoing maintenance expenses | Ensure sufficient savings and pre-approval status |
| Market Conditions | Opportunities in a competitive market | Inventory shortages in some areas; broader economic uncertainties | Stay updated with economic indicators and market reports |
Additional Strategic Considerations
Leveraging Tax Advantages
One significant benefit of homeownership is the array of tax advantages available. Mortgage interest, property taxes, and even certain closing costs may be tax deductible. These benefits can help offset the high upfront expenses and improve your long-term financial outlook. Collaborate with a tax professional to maximize these benefits while ensuring compliance with current tax regulations.
Future-Proofing Your Investment
Evaluate potential future changes in your life that might impact how you live in your new home. Consider factors such as career stability, family growth, and changing neighborhood dynamics. A property that meets your needs today should ideally have the capacity to serve you well in the years to come. This forward-thinking approach helps protect your investment against market volatility and offers greater personal satisfaction.
Navigating the Emotional Journey
The emotional components of buying a home cannot be overlooked. The decision often evokes feelings of achievement and hope as you create a space to call your own. Nevertheless, it is important to acknowledge that the process may include periods of stress—be it due to negotiating a deal or handling unexpected repairs. A balanced approach, which combines careful research with emotional readiness, will empower you to navigate both the challenges and the wonderful opportunities that homeownership provides.
References
- Buy Home in 2025 - The American House
-
Should I Buy a House Now? - U.S. News
- Expert Tips on Buying a Home - CNET Personal Finance
- Is 2025 the Year to Buy a Home? - Bankrate
- House Buying Guide for 2025 - Investopedia
Recommended Queries for Further Insights
Last updated March 21, 2025