
Unlocking True Performance: Demystifying Risk-Adjusted Returns in Diversified Mutual Fund Portfolios
Go beyond raw returns to understand the efficiency of your multi-scheme, multi-asset class investments.
Key Insights into Risk-Adjusted Returns
- Comprehensive Evaluation: Risk-adjusted return metrics provide a holistic view of portfolio performance by factoring in the level of risk taken to achieve returns, essential for comparing diverse mutual fund schemes and asset classes.
- Core Metrics: The Sharpe Ratio, Sortino Ratio, Treynor Ratio, and Alpha are fundamental tools for assessing how efficiently a portfolio generates returns relative to its associated risk.
- Portfolio Aggregation: For portfolios with multiple schemes and asset classes, individual scheme metrics are aggregated using weighted averages, considering asset allocation and the correlation between assets to accurately reflect overall portfolio risk and return.
The Essence of Risk-Adjusted Return
Understanding risk-adjusted return is crucial for investors, especially when managing a mutual fund portfolio that spans different schemes and asset classes. Simply looking at raw returns can be misleading, as higher returns often come with higher risk. Risk-adjusted return quantifies how much profit an investment generates for the amount of risk undertaken. This allows for a fair comparison between investments with varying risk profiles, helping investors identify which investments are truly efficient in their return generation.
For a portfolio comprising diverse elements like equity funds, debt funds, and hybrid funds, which inherently touch upon various asset classes (stocks, bonds, real estate, etc.), the concept of risk-adjusted return becomes even more vital. Each asset class carries distinct risk and return characteristics; for instance, equities generally offer higher growth potential but come with greater volatility, while bonds provide stability with typically lower returns. Evaluating these elements in isolation misses the crucial interplay of diversification and risk management within a cohesive portfolio.
Why Raw Returns Aren't Enough
Imagine two mutual funds. Fund X yields 15% annually but experiences wild swings in value. Fund Y yields 12% annually but maintains a much more stable performance. While Fund X has a higher raw return, Fund Y might offer a better risk-adjusted return, meaning it delivers more return for each unit of risk taken. This efficiency is what risk-adjusted metrics aim to capture, allowing investors to make decisions that align with their personal risk tolerance and financial goals.
Core Metrics for Measuring Risk-Adjusted Returns
Several statistical measures, grounded in modern portfolio theory (MPT), are commonly used to assess the risk and risk-adjusted performance of mutual funds within a diversified portfolio. These metrics help investors understand the efficiency of their investments:
The Sharpe Ratio: Total Risk Efficiency
The Sharpe Ratio is perhaps the most widely recognized metric for risk-adjusted return, developed by Nobel laureate William F. Sharpe. It measures the excess return of an investment (or portfolio) over the risk-free rate, per unit of total risk (standard deviation).
Formula:
\[ \text{Sharpe Ratio} = \frac{R_p - R_f}{\sigma_p} \]Where:
- \(R_p\) = Portfolio's average return
- \(R_f\) = Risk-free rate of return (e.g., yield on a 10-year government bond)
- \(\sigma_p\) = Standard deviation of the portfolio's returns (total volatility)
A higher Sharpe Ratio indicates better risk-adjusted performance, implying the portfolio is generating more return for each unit of total risk assumed. It's particularly useful for comparing funds or portfolios regardless of their absolute volatility.
The Sortino Ratio: Focusing on Downside Risk
Similar to the Sharpe Ratio, the Sortino Ratio enhances the analysis by focusing specifically on downside risk. It measures the excess return over the risk-free rate, divided by the downside deviation. Downside deviation only considers the volatility of negative returns, making it a valuable metric for risk-averse investors concerned with capital preservation.
Formula:
\[ \text{Sortino Ratio} = \frac{R_p - R_f}{\sigma_{down}} \]Where:
- \(R_p\) = Portfolio's average return
- \(R_f\) = Risk-free rate of return
- \(\sigma_{down}\) = Downside deviation of the portfolio's returns (volatility of negative returns)
A higher Sortino Ratio suggests a lower probability of significant losses relative to the returns generated, highlighting a fund's effectiveness in managing negative volatility.
The Treynor Ratio: Systematic Risk Efficiency
The Treynor Ratio evaluates the return earned in excess of the risk-free rate per unit of systematic risk, measured by beta. Systematic risk is the market-related risk that cannot be diversified away.
Formula:
\[ \text{Treynor Ratio} = \frac{R_p - R_f}{\beta_p} \]Where:
- \(R_p\) = Portfolio's average return
- \(R_f\) = Risk-free rate of return
- \(\beta_p\) = Portfolio's beta (sensitivity to market movements)
This ratio is especially useful for portfolios where market exposure is a primary concern, such as equity-heavy portfolios, as it assesses performance relative to the unavoidable market fluctuations.
Alpha: Manager Skill and Outperformance
Alpha measures the excess return of a fund or portfolio compared to its expected return, given its beta. A positive alpha indicates that the fund manager has generated returns beyond what the market or benchmark would suggest, showcasing their skill in selecting securities or timing the market.
Formula:
\[ \alpha = R_p - [R_f + \beta_p (R_m - R_f)] \]Where:
- \(R_p\) = Portfolio's actual return
- \(R_f\) = Risk-free rate of return
- \(\beta_p\) = Portfolio's beta
- \(R_m\) = Benchmark market return
Alpha helps investors understand if a fund's outperformance is due to genuine managerial expertise or merely taking on more market risk.
Other Important Risk Measures
- Standard Deviation: Quantifies the total volatility or variability of a fund's returns around its average return. A higher standard deviation signifies greater risk due to wider fluctuations in returns.
- Beta: Measures a mutual fund's volatility relative to an overall market benchmark. A beta of 1.0 means the fund moves in line with the market, while a beta greater than 1.0 indicates higher volatility.
- R-squared: Indicates the correlation of a mutual fund's performance with its benchmark index, on a scale of 0 to 100. An R-squared of 100 means perfect correlation, helping investors understand how much of a fund's movements are explained by its benchmark.
Step-by-Step Calculation for a Diversified Portfolio
Calculating risk-adjusted returns for a mutual fund portfolio that includes various schemes and asset classes requires a systematic approach:
Step 1: Gather Comprehensive Data
Collect historical data for each individual mutual fund scheme and asset class within your portfolio. This includes:
- Periodic Returns (Rp): Obtain daily, monthly, or annual returns for each scheme over a consistent time horizon (e.g., 3-5 years).
- Risk-Free Rate (Rf): A reliable proxy is the yield on a long-term government bond (e.g., 10-year Treasury bond).
- Individual Scheme Volatility (Standard Deviation, Beta, Downside Deviation): These figures are often available in fund fact sheets, mutual fund analysis platforms, or financial data providers.
- Benchmark Market Return (Rm): Relevant market indices (e.g., Nifty, Sensex for Indian equities; broad bond indices for debt) to compare against.
Step 2: Calculate Individual Scheme Metrics
Before aggregating, it's beneficial to calculate the risk-adjusted metrics for each individual scheme. For example, if you have an equity fund and a debt fund:
// Example Calculation for an Equity Fund (Scheme A)
const equityFundReturn = 0.12; // 12%
const equityFundStdDev = 0.18; // 18%
const equityFundBeta = 1.2;
const riskFreeRate = 0.04; // 4%

const sharpeRatioEquity = (equityFundReturn - riskFreeRate) / equityFundStdDev;
// sharpeRatioEquity = (0.12 - 0.04) / 0.18 = 0.44

const treynorRatioEquity = (equityFundReturn - riskFreeRate) / equityFundBeta;
// treynorRatioEquity = (0.12 - 0.04) / 1.2 = 0.0667 (or 6.67%)
Perform similar calculations for all schemes in your portfolio.
Step 3: Aggregate for the Overall Portfolio
The key to a multi-scheme, multi-asset portfolio calculation is to account for the diversification benefits. Portfolio risk is not simply the weighted average of individual scheme risks, as assets do not typically move in perfect tandem. Their correlation plays a significant role.
Calculating Weighted Average Portfolio Return
This is straightforward: multiply each scheme's return by its allocation weight and sum the results.
Formula:
\[ R_p = \sum_{i=1}^n (w_i \times R_i) \]Where:
- \(R_p\) = Overall portfolio return
- \(w_i\) = Weight (allocation percentage) of scheme i
- \(R_i\) = Return of scheme i
Example: If Scheme A (Equity) is 60% of portfolio with 15% return, and Scheme B (Bonds) is 40% with 6% return:
\[ R_p = (0.60 \times 0.15) + (0.40 \times 0.06) = 0.09 + 0.024 = 0.114 \text{ or } 11.4\% \]Calculating Portfolio Standard Deviation (Total Risk)
This is more complex and involves the covariance (or correlation) between the schemes. For a portfolio with two schemes:
\[ \sigma_p = \sqrt{w_A^2 \sigma_A^2 + w_B^2 \sigma_B^2 + 2 w_A w_B \sigma_A \sigma_B \rho_{AB}} \]Where:
- \(w_A, w_B\) = Weights of Scheme A and B
- \(\sigma_A, \sigma_B\) = Standard deviations of Scheme A and B
- \(\rho_{AB}\) = Correlation coefficient between Scheme A and B
For more than two assets, a covariance matrix is used to calculate portfolio variance:
\[ \sigma_p^2 = \sum_{i=1}^n \sum_{j=1}^n w_i w_j \sigma_i \sigma_j \rho_{ij} \]Then, \(\sigma_p = \sqrt{\sigma_p^2}\).
This formula captures how diversification reduces overall portfolio risk when assets are not perfectly correlated. For instance, if stocks and bonds often move in opposite directions (negative correlation), combining them can reduce the portfolio's overall volatility.
Calculating Portfolio Beta (Systematic Risk)
The portfolio beta is typically a weighted average of the individual betas of the schemes, assuming their betas are calculated against the same market benchmark:
\[ \beta_p = \sum_{i=1}^n (w_i \times \beta_i) \]Where:
- \(\beta_p\) = Overall portfolio beta
- \(w_i\) = Weight of scheme i
- \(\beta_i\) = Beta of scheme i
Step 4: Compute Portfolio-Level Risk-Adjusted Metrics
Once you have the overall portfolio return (\(R_p\)), portfolio standard deviation (\(\sigma_p\)), and portfolio beta (\(\beta_p\)), you can calculate the aggregated risk-adjusted metrics using the formulas provided earlier:
- Portfolio Sharpe Ratio: \(\frac{R_p - R_f}{\sigma_p}\)
- Portfolio Sortino Ratio: \(\frac{R_p - R_f}{\sigma_{down_p}}\) (where \(\sigma_{down_p}\) is the portfolio downside deviation)
- Portfolio Treynor Ratio: \(\frac{R_p - R_f}{\beta_p}\)
- Portfolio Alpha: \(R_p - [R_f + \beta_p (R_m - R_f)]\)
Visualizing Risk-Adjusted Performance
To further illustrate the concept of risk-adjusted performance across different investment facets, consider a radar chart. This chart helps to visualize how various investment aspects, including different risk-adjusted metrics, contribute to the overall evaluation of a mutual fund portfolio.
The radar chart below compares a hypothetical balanced portfolio with a more aggressive, equity-heavy portfolio across various dimensions important for risk-adjusted analysis. It highlights how a diversified portfolio, by strategically combining different asset classes, can achieve a favorable balance of returns and risk mitigation, potentially leading to stronger risk-adjusted performance compared to a less diversified or more volatile strategy.
Radar chart comparing a balanced and aggressive portfolio on risk-adjusted metrics and related factors.
The Role of Asset Classes and Diversification
In a mutual fund portfolio, asset allocation—the mix of different asset classes like equities, fixed income, and alternatives—is a primary driver of both risk and return. Each asset class has unique characteristics that influence the overall portfolio's risk-adjusted performance.
For example, equities (stocks) typically offer higher growth potential but come with greater volatility, resulting in higher standard deviations and betas. Fixed income (bonds) generally provides stability and lower volatility, which can help cushion the portfolio during market downturns. By combining these asset classes, especially those with low or negative correlation, investors can often achieve a better risk-adjusted return for the overall portfolio than by investing in a single asset class.
This diversification benefit is crucial. When assets move in different directions, the negative performance of one asset class can be offset by the positive performance of another, reducing the overall portfolio's volatility without necessarily sacrificing returns. This strategic mixing is at the heart of improving risk-adjusted returns.
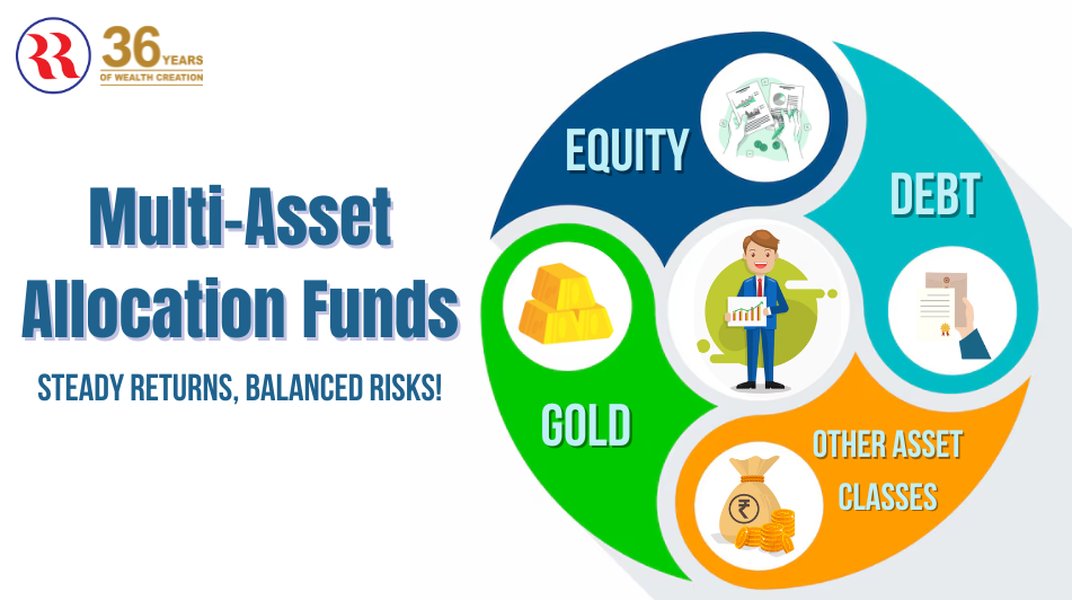
Multi-Asset Allocation Funds aim to diversify across various asset classes to optimize risk-adjusted returns.
Understanding Asset Class Behavior
The following table summarizes typical characteristics of common asset classes in terms of their risk and return profiles, and how they contribute to a diversified portfolio:
| Asset Class | Typical Risk Level | Typical Return Potential | Role in Portfolio |
|---|---|---|---|
| Equities (Stocks) | High | High | Growth, long-term capital appreciation |
| Fixed Income (Bonds) | Low to Medium | Low to Medium | Stability, income generation, diversification |
| Cash & Equivalents | Very Low | Very Low | Liquidity, capital preservation, short-term holding |
| Real Estate | Medium to High | Medium to High | Inflation hedge, income, diversification (lower correlation to stocks/bonds) |
| Commodities | High | Variable | Inflation hedge, diversification (lower correlation to traditional assets) |
The Power of Portfolio Diversification
The concept of portfolio diversification is paramount in managing risk and optimizing risk-adjusted returns, particularly when dealing with mutual funds across different schemes and asset classes. Diversification helps mitigate specific risks associated with individual investments, improving the overall efficiency of the portfolio. The mindmap below illustrates the key components and benefits of diversifying a mutual fund portfolio.
By spreading investments across various schemes (e.g., large-cap, mid-cap, sectoral funds) and asset classes (equities, debt, gold), investors can reduce the impact of poor performance from any single investment. This strategic allocation helps to smooth out returns and reduce overall portfolio volatility, ultimately enhancing risk-adjusted returns.
Mindmap illustrating the key elements and benefits of portfolio diversification in mutual funds.
Practical Tools and Considerations
While manual calculation of these metrics, especially portfolio standard deviation with multiple assets, can be complex, several tools and resources simplify the process:
- Online Portfolio Analyzers: Platforms like Portfolio Visualizer and SmartAsset allow users to input their portfolio holdings (including weights across different asset classes) and automatically calculate various risk-adjusted metrics, often with backtesting capabilities.
- Mutual Fund Risk Calculators: Many Asset Management Companies (AMCs) and financial portals provide online tools that can compute scheme-specific risk metrics.
- Spreadsheet Software (e.g., Excel): For those comfortable with formulas, Excel can be used to calculate weighted returns, standard deviation (using covariance matrices), and other metrics.
- Fund Documents: Mutual fund fact sheets and Scheme Information Documents (SIDs) often disclose historical standard deviation, beta, and Sharpe ratios for individual schemes, which can be aggregated for portfolio-level analysis.
Important Considerations:
- Historical Data Limitation: Remember that historical performance and risk metrics do not guarantee future results. Market conditions can change, affecting correlations and volatilities.
- Risk Profiling: Before constructing a portfolio, it is vital to determine your personal risk tolerance. Online tools and questionnaires can help assess your risk appetite, which in turn guides the appropriate percentage of your portfolio to be exposed to different asset classes.
- Correlation: The correlation between different asset classes is a critical factor in true diversification. Assets with low or negative correlation can significantly reduce overall portfolio risk.
- Regular Review: Periodically review and rebalance your portfolio to ensure it remains aligned with your risk tolerance and financial objectives, and to adjust to changing market conditions.
Further Deep Dive: Asset Allocation and Risk
Understanding how asset allocation influences risk and return is fundamental to constructing a robust mutual fund portfolio. The choice of how much to allocate to stocks versus bonds, for instance, is one of the most impactful decisions an investor makes, directly affecting the portfolio's expected returns and overall risk profile.
The following video provides an excellent overview of choosing an asset allocation and its implications for risk and return. It explains how different asset classes interact and how strategic allocation can help manage portfolio risk effectively, aligning with your financial goals.
"Choosing an Asset Allocation (How Much in Stocks vs. Bonds?)" - This video explores how asset allocation is a critical determinant of expected investment returns and overall portfolio risk.
This video contextualizes why diversified portfolios require careful consideration of each asset class's contribution to overall risk and return. It reinforces the idea that smart allocation can be a powerful tool for optimizing risk-adjusted performance.
Frequently Asked Questions (FAQ)
What is a good Sharpe Ratio?
Can I calculate risk-adjusted return in Excel?
Why is the Sortino Ratio important for risk-averse investors?
How does diversification impact risk-adjusted returns?
Conclusion
Calculating risk-adjusted return in a mutual fund portfolio with different schemes and asset classes is essential for a thorough evaluation of investment performance. By utilizing metrics such as the Sharpe Ratio, Sortino Ratio, Treynor Ratio, and Alpha, investors can move beyond mere raw returns to understand how efficiently their portfolio generates profit relative to the risk taken. The process involves aggregating individual scheme data, computing weighted portfolio returns and risks (accounting for diversification benefits through correlation), and then applying the appropriate risk-adjusted formulas. Employing practical tools like online portfolio analyzers and understanding the unique characteristics of various asset classes further empowers investors to construct and manage diversified portfolios that align with their financial goals and risk tolerance.
Recommended Further Reading
- How to select mutual funds based on risk-adjusted performance?
- Understanding the correlation between asset classes in portfolio management.
- Advanced portfolio optimization techniques for diversified investments.
- The impact of rebalancing on risk-adjusted returns in mutual fund portfolios.