
Navigating the Complexities of Contingent Business Interruption Coverage: A Comprehensive Guide
Protecting Your Business from Third-Party Disruptions and Supply Chain Vulnerabilities
Key Insights into CBI Coverage
- Contingent Business Interruption (CBI) insurance is a vital extension of standard business interruption policies, specifically designed to cover financial losses when a third-party entity—such as a key supplier, customer, or service provider—experiences a disruption that impacts your business's operations.
- CBI policies typically compensate for lost net income, continuing expenses, and extra expenses incurred due to the third-party shutdown, even if your own business property remains undamaged.
- This coverage is particularly crucial for businesses with interdependent supply chains, those heavily reliant on a few key partners, or those whose operations are significantly affected by "leader properties" (nearby attractions or businesses that generate customer traffic).
Understanding Contingent Business Interruption (CBI) Coverage
Contingent Business Interruption (CBI) insurance, often referred to as Dependent Business Interruption insurance, is a specialized form of coverage that safeguards businesses against financial losses stemming from disruptions in the operations of critical third-party entities. Unlike traditional business interruption insurance, which covers losses due to direct physical damage to your own property, CBI steps in when an insured peril affects a supplier, customer, or other vital external partner, subsequently impacting your ability to operate and generate revenue.
In today's interconnected global economy, businesses rarely operate in isolation. Supply chains are intricate webs, and reliance on external entities—whether for raw materials, finished products, distribution, or even customer traffic—is commonplace. A disruption at any point in this chain can have a cascading effect, leading to significant financial setbacks for your business. CBI insurance is specifically designed to mitigate these "ripple effect" risks, providing a crucial safety net for companies whose prosperity is intrinsically linked to the continuous operation of others.
The Core Purpose of CBI Insurance
The primary purpose of CBI insurance is to reimburse policyholders for financial losses when their business is interrupted due to a covered peril affecting property not owned, operated, or controlled by the insured. This includes:
- Lost Net Income: Compensation for the profits your business would have earned had the third-party disruption not occurred.
- Continuing Expenses: Coverage for ongoing operational costs that persist even during the interruption, such as payroll, rent, utilities, and loan payments, which do not cease despite the halt in revenue.
- Extra Expenses: Reimbursement for additional costs incurred to minimize the period of interruption or to restore operations as quickly as possible. This might include renting temporary facilities, expediting shipments, or paying overtime to employees.
Essentially, CBI aims to put your business in the same financial position it would have been in had the third-party disruption not happened. It's a proactive measure to protect against unforeseen events that lie outside your direct control but directly impact your bottom line.
When CBI Coverage Comes into Play: Real-World Scenarios
CBI insurance is invaluable in a variety of scenarios where a business's operations are affected by external factors. Here are common examples:
Supplier Disruptions
Many businesses rely heavily on one or a few key suppliers for raw materials, components, or finished goods. If a supplier's facility is damaged by an insured peril (e.g., fire, natural disaster), preventing them from delivering essential items, your business might face a production halt or an inability to fulfill customer orders. CBI coverage would then compensate for the lost income and extra expenses incurred during this period.
For instance, if a manufacturing plant depends on a single supplier for specialized microchips, and that supplier's facility is damaged by fire, leading to a partial interruption in chip production, the manufacturer could incur significant losses. CBI coverage would help offset these financial impacts.
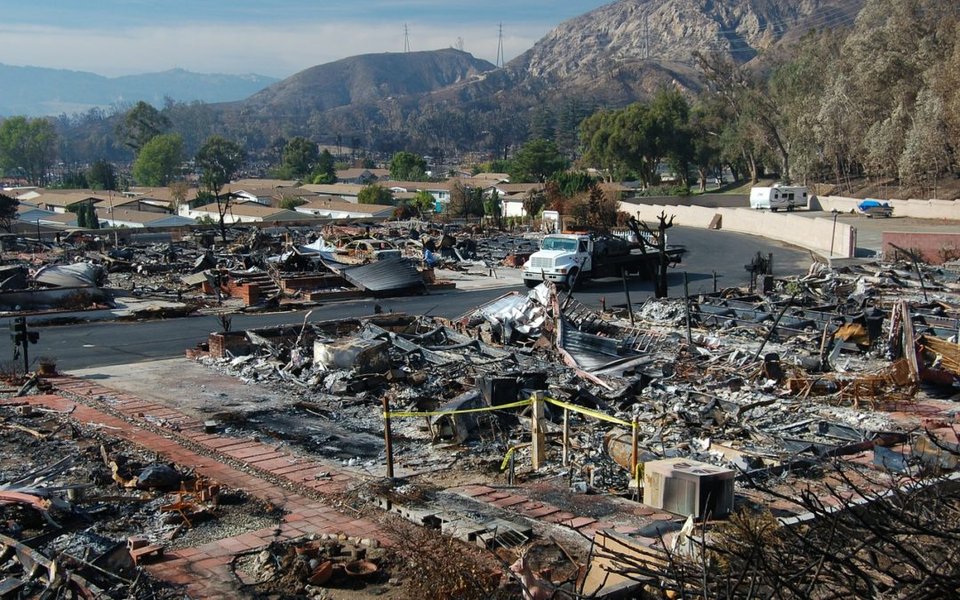
An example of fire damage that could impact a supplier, triggering CBI coverage.
Customer Disruptions
Similarly, if a significant portion of your revenue comes from one or a small number of major customers, a disruption at their premises can directly impact your sales. For example, if you are a clothing manufacturer and 90% of your products are sold through a single retail chain, and that chain's flagship store is flooded and forced to shut down for several weeks, your business would experience a substantial loss of sales. CBI coverage can help you recover these lost earnings.
Leader Property Disruptions
Some businesses, particularly those in retail or hospitality, depend on foot traffic or ancillary services generated by a nearby "leader property" like a large mall, an amusement park, or a major tourist attraction. If this leader property suffers physical damage from a covered peril and is forced to close, it can significantly reduce customer flow to your business. The 2010 Deepwater Horizon oil spill, for example, impacted many Gulf-area businesses that relied on tourism, as would-be vacationers opted for other destinations.
Cyber-Related Interruptions
In the digital age, cyber threats are a growing concern. Many businesses rely on third-party IT service providers, cloud hosting services, or payment processors. A cyber-attack or system outage at one of these providers can directly interrupt your online operations, leading to lost revenue and extra expenses. CBI coverage has evolved to include such cyber-related disruptions, covering losses when, for instance, an online retailer's website becomes inaccessible due to an outage at their outsourced web hosting provider.
The radar chart above illustrates the relative importance of Contingent Business Interruption (CBI) coverage across various risk dimensions compared to a typical business's exposure without such protection. It highlights how CBI coverage is essential for mitigating risks associated with reliance on external parties, particularly in areas like cyber third-party outages and complex supply chains where inherent business exposure can be significant. The 'Importance of CBI Coverage' dataset demonstrates a higher level of protective value across all axes, emphasizing its role in safeguarding against indirect disruptions.
Distinguishing CBI from Standard Business Interruption Insurance
It's crucial to understand the fundamental difference between standard Business Interruption (BI) insurance and Contingent Business Interruption (CBI) insurance. While both cover lost income and ongoing expenses due to business disruptions, the trigger for coverage is distinct:
| Feature | Standard Business Interruption (BI) | Contingent Business Interruption (CBI) |
|---|---|---|
| Trigger Event | Direct physical damage to the insured's own property (e.g., your factory, office, or store) caused by a covered peril. | Physical damage or covered peril affecting a third-party property (supplier, customer, leader property) that *then* impacts your business. |
| Property Location | On your premises. | At a third-party's premises, not owned or controlled by you. |
| Coverage Focus | Losses from your direct operational shutdown. | Losses from your indirect operational shutdown due to external entities. |
| Examples | Your warehouse floods; your equipment breaks down; your office catches fire. | Your sole raw material supplier's factory burns down; a major customer's distribution center is hit by a tornado; a cyber attack disables your cloud provider. |
While standard BI insurance is typically an extension of your commercial property policy, CBI is often an extension of your BI policy, specifically addressing the broader ecosystem of interdependencies that define modern business. Businesses with intricate supply chains or significant reliance on specific external partners should seriously consider adding CBI coverage.
Coverage Period and Limitations
CBI coverage typically kicks in from the date of the covered peril affecting the third party and usually ends when the damaged third-party property is physically repaired and returned to operation, or when your business is fully restored to its pre-loss operational capacity. It's important to note that CBI coverage is often sub-limited to amounts well below the broader business interruption limits. These sub-limits can sometimes be low and not commensurate with the full extent of potential loss exposure, making it crucial to assess your vulnerabilities and discuss appropriate limits with your insurer.
Who Needs Contingent Business Interruption Coverage?
CBI insurance is not a one-size-fits-all solution; its necessity depends heavily on your business model and its dependencies. You should consider CBI coverage if:
- You rely heavily on a single or a small number of suppliers for raw materials, components, or finished products.
- One or a few major customers account for a significant portion of your sales and revenue.
- Your business depends on traffic or services from a nearby retail business or attraction (a "leader property").
- You outsource critical IT functions, cloud services, or payment processing to third-party providers.
- Your supply chain is complex, global, or involves just-in-time inventory practices, making it highly susceptible to disruptions.
Industries that commonly benefit from CBI include manufacturing, retail, hospitality, technology, and healthcare, particularly those with specialized supply chains or significant customer concentrations. Conversely, a small law firm, for example, might not rely on specific suppliers or vendors to the extent that a third-party disruption would force it to close, making CBI less critical for such a business.
Why CBI is Essential for Modern Businesses
In an increasingly interdependent global marketplace, 70% of downtime is reportedly third-party caused. This highlights the critical need for businesses to protect themselves from interruptions caused by issues with third-party vendors, suppliers, and technology providers. CBI coverage provides peace of mind, allowing businesses to withstand unexpected disruptions that they cannot anticipate or control directly.
This video explains what Contingent Business Interruption (CBI) Insurance is and how it helps safeguard your operations from external disruptions. It provides a concise overview of how CBI coverage protects businesses that rely on third-party suppliers or customers.
Frequently Asked Questions (FAQ) about CBI Coverage
What types of losses does CBI insurance cover?
Is CBI insurance the same as standard Business Interruption insurance?
What kinds of third parties are covered under CBI?
Does CBI coverage apply to utility interruptions?
How can I determine if my business needs CBI coverage?
Conclusion
Contingent Business Interruption (CBI) insurance is an indispensable component of a robust risk management strategy for businesses operating in today's highly interconnected world. By extending coverage beyond direct physical damage to your own property, CBI addresses the significant financial vulnerabilities that arise from disruptions within your supply chain or at the premises of crucial external partners. It provides compensation for lost income and extra expenses, ensuring that your business can navigate unforeseen third-party challenges and maintain financial stability. Understanding your business's unique dependencies and working closely with an insurance expert are key steps in securing appropriate CBI coverage that aligns with your specific risk exposures.
Recommended Further Reading
- How does standard business interruption insurance work?
- What are the key considerations for supply chain risk management?
- Cyber insurance policies and third-party risk coverage
- The role of leader property coverage in business insurance?