
Ethos India Ltd Research Reports Analysis
In-depth overview of financial performance, market positioning, and growth prospects of India’s leading luxury watch retailer
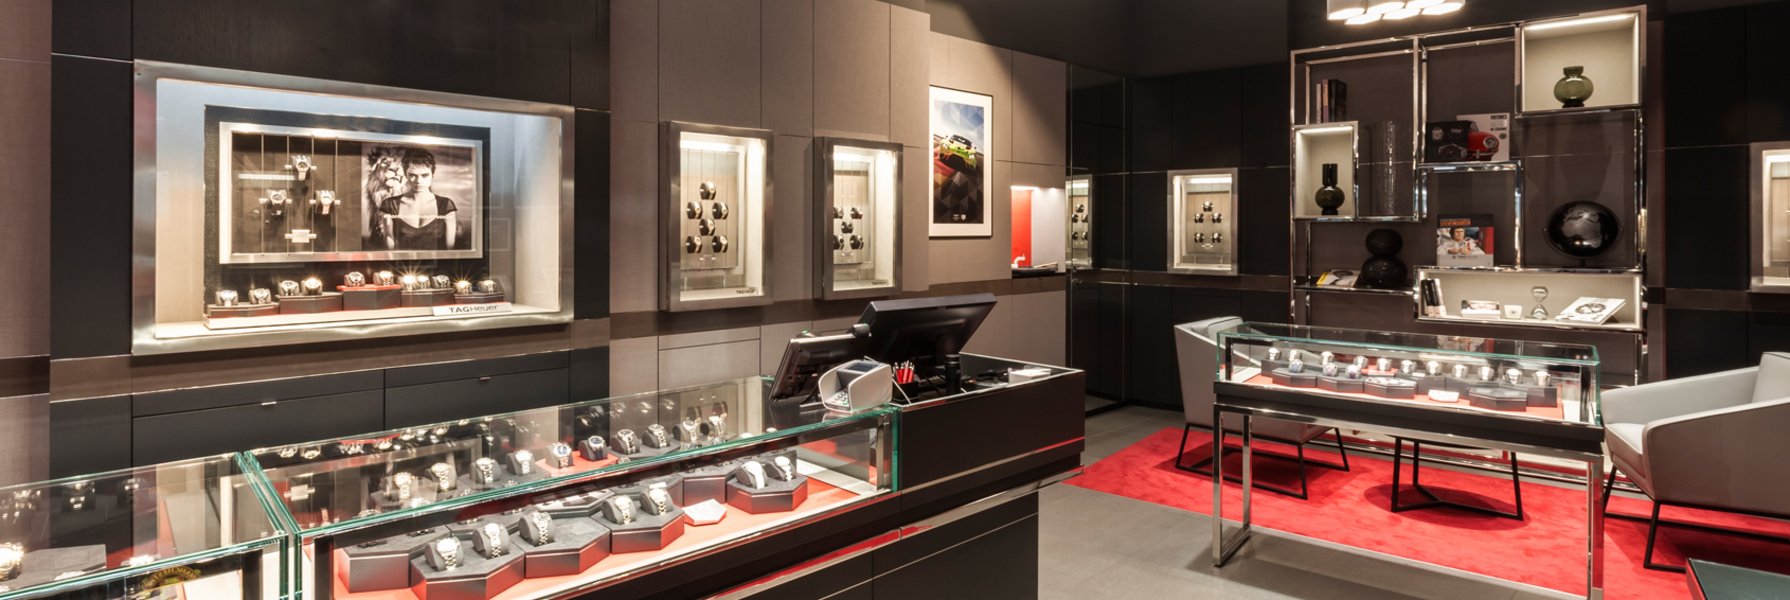
Highlights
- Robust Financial Growth: Ethos India Ltd has consistently delivered strong revenue and profit growth, reflecting its ability to capture market share in a competitive luxury segment.
- Market Leadership and Expansion: The company is recognized as India's largest luxury and premium watch retailer and is aggressively expanding its footprint across major cities and emerging markets.
- Diversification and Strategic Initiatives: Ethos is not only focused on luxury watches but is diversifying into related luxury segments, bolstering its growth prospects.
Introduction
Ethos India Ltd operates as India’s largest luxury and premium watch retailer, offering a diverse portfolio of internationally renowned luxury watch brands. The company's success is built on robust financial performance, strategic market positioning, and continuous expansion plans. This analysis synthesizes findings from various data points to present a comprehensive review of Ethos India Ltd based on recently published research reports and financial highlights.
Company Profile and Market Position
Company Background
Established several years ago and being promoted by a renowned parent company, Ethos India Ltd has rapidly grown into a market leader in India’s luxury watch retail segment. It operates over 63 retail stores across 24 cities, showcasing more than 65 premium international watch brands. Ethos India Ltd’s market share reflects its deep penetration in both the premium and exclusive luxury segments, with approximately 13% share in the overall premium segment and about 20% in the exclusive luxury segment.
Strategic Market Position
Ethos's strategic positioning is reinforced by its vast network of physical stores complemented by an evolving online presence. The company’s ability to imbue customer experience with a blend of digital innovation and personalized retail service has further solidified its prominence in the luxury segment. With a strong market share and brand reputation, Ethos is positioned as a go-to destination for luxury watches in India.
Expansion Highlights
Ethos has ambitious expansion plans that include the opening of additional retail outlets. With plans to add 25 new stores in the near term and a long-term vision to add over 100 stores in the next few years, the company aims at capturing untapped markets in Tier 2 and Tier 3 cities. This expansion is expected to drive incremental revenue and further cement its leadership position in the industry.
Financial Performance Overview
Revenue and Profit Trends
Ethos India Ltd has showcased a trend of solid financial performance over recent quarters. In Q3 FY25, the company reported revenue of ₹369 crore, marking an impressive year-over-year growth of over 31%. Concurrently, net profit reached ₹29.48 crore, showing a growth of 15.6% compared to the previous year. These figures indicate that Ethos has managed to enhance its profitability even as it continues to expand its market presence.
H1 FY25 Performance Metrics
Over the first half of FY25, Ethos recorded a revenue of ₹570.4 crore, representing a year-over-year growth rate of 22.6%. The company’s EBITDA reached ₹98 crore, a growth of 22.2%, whereas the profit after tax (PAT) increased by 19.9% to reach ₹44 crore. Such robust performance metrics underscore Ethos's capability to sustain high margins and manage cost efficiencies effectively.
Stock Performance and Analyst Ratings
Ethos India Ltd is widely covered by market analysts, with reports consistently reflecting a positive long-term outlook. Multiple research reports have initiated coverage with a BUY rating. On an average, analysts have priced the company’s shares at a target around ₹3,340, indicating significant upside potential from the current market levels. While some technical analyses suggest caution by signaling trends like a sell signal in specific contexts, fundamental analysis and growth projections remain predominantly bullish.
Valuation and Growth Estimates
In addition to the healthy revenue and profit growth, valuation models have been supportive of Ethos's long-term investment case. The current consensus on share price targets, ranging from a minimum estimate of approximately ₹3,300 to a maximum nearing ₹3,703, provides investors with confidence in the company’s future earnings potential. The varying estimates also highlight a robust liquidity position and the ability to capitalize on market opportunities, even when faced with headwinds like currency fluctuations.
Strategic Initiatives and Expansion Plans
Omnichannel and Digital Expansion
A crucial part of Ethos population’s future growth strategy lies in its focus on digital innovation and omnichannel retailing. By incorporating state-of-the-art e-commerce solutions, Ethos has managed to integrate its physical stores with digital platforms seamlessly. This integration not only optimizes order management and enhances the overall customer experience but also reinforces brand loyalty in an increasingly digital retail landscape.
Diversification into New Luxury Segments
Although Ethos is primarily known for its premium watch offering, the company is strategically diversifying its product portfolio. Recent initiatives include ventures into complementary luxury segments such as jewelry and high-end accessories. Some reports also highlight a move into related verticals like luxury luggage, leveraging strategic brand partnerships. This diversification strategy is designed to mitigate sector-specific risks while tapping into broader luxury consumer spending trends.
Store Network and Geographic Expansion
Ethos has been aggressively expanding its physical retail network by adding new stores in quick succession across major metropolitan areas as well as in emerging markets. Based on current projections, along with the planned addition of 25 new stores in the near term, the company envisions further expansion into Tier 2 and Tier 3 cities. Ethos’s retailer network not only enhances its brand visibility but also serves as a key driver for revenue growth due to increased accessibility in previously under-penetrated markets.
Table: Key Financial Metrics for Recent Quarters
| Period | Revenue (₹ Crore) | Net Profit (₹ Crore) | EBITDA (₹ Crore) | PAT (₹ Crore) | YoY Growth |
|---|---|---|---|---|---|
| Q3 FY25 | 369 | 29.48 | - | - | 31.54%/15.6% |
| H1 FY25 | 570.4 | - | 98 | 44 | 22.6% / 22.2% / 19.9% |
| Q1 FY25 | 273 | - | - | - | ~19% |
Challenges and Risks
Currency Fluctuations
Like many players in the premium retail segment, Ethos faces certain macroeconomic risks. One major concern is currency volatility, particularly fluctuations in the INR relative to foreign currencies such as CHF, which could increase the cost of imported luxury watches and thereby impact margins. In scenarios of currency depreciation, the cost burden may transfer to consumers, potentially affecting sales volume.
Competitive Pressure
Competition within the luxury retail sector remains intense, especially with numerous international and domestic brands vying for consumer attention. Increased competition could create pricing pressures and challenge Ethos’s ability to sustain its current market share. Despite these challenges, the company’s brand strength and well-established market presence provide a robust buffer against competitive threats.
Operational and Supply Chain Risks
Expanding retail operations invariably comes with challenges related to inventory management, supply chain logistics, and market adaptability. Ethos must continuously innovate and scale its operational systems—particularly in its omnichannel strategy—to manage these risks effectively. Investments in technology, such as advanced order management systems, are crucial to minimizing potential disruptions and maintaining a seamless customer experience.
Table: Key Risks and Mitigation Strategies
| Risk | Description | Mitigation Strategy |
|---|---|---|
| Currency Volatility | Fluctuations in exchange rates could impact import costs. | Hedging strategies and pricing adjustments. |
| Competitive Pressure | Increased market competition could erode market share. | Strengthening exclusive partnerships and enhancing customer experience. |
| Supply Chain Disruptions | Operational risks related to inventory management and logistics. | Investing in robust supply chain and digital order management systems. |
Future Growth Prospects
Market Expansion Through New Stores
The future growth trajectory for Ethos is anchored in its robust expansion strategy. With plans to add a significant number of stores both in metropolitan regions and smaller cities, Ethos is set to capture a broader segment of the luxury consumer market. New store openings not only boost immediate revenues but also ensure long-term brand engagement by tapping into consumer segments that were previously under-served.
Diversification into Broader Luxury Categories
Beyond expanding its physical footprint, the company is actively diversifying into new luxury categories. This strategic diversification aims to leverage the existing brand strength and deepen customer relationships by offering a broader range of luxury products including high-end jewelry and premium accessories. By doing so, Ethos mitigates risks inherent to reliance on a single product category and establishes multiple revenue streams.
Leveraging Digital Transformation
Ethos is making significant investments in digital transformation, which is key to sustaining long-term growth. The integration of advanced digital technologies in its retail operations has improved both the customer journey and overall operational efficiency. With a robust omnichannel strategy, Ethos is well-positioned to optimize its marketing, order management, and after-sales service processes. This digital shift not only contributes to current revenue improvements but also sets a solid foundation for future scalability.
Impact of Economic Factors
The broader economic environment plays a critical role in shaping future growth. Increased consumer spending on luxury goods, driven by rising disposable incomes in India, supports Ethos's expansion strategy. Moreover, anticipated gradual reductions in import duties and supportive government policies for the luxury market further boost growth prospects. In light of these factors, Ethos’s strategic investments in technology, store expansion, and diversification are expected to create a resilient growth model.
In-depth Financial Analysis and Market Valuation
Share Price and Upside Potential
A comprehensive evaluation of Ethos’s financials reveals a compelling investment case supported by strong top-line growth and consistent profit margins. Analysts have consistently maintained a BUY rating for Ethos’s stock. The average share price target based on current assessments hovers around ₹3,340, with some estimates suggesting a range between approximately ₹3,300 and ₹3,703. Such figures reflect an estimated upside of 27% to over 35% compared to the current market price, making Ethos an attractive proposition for long-term investors.
Earnings Growth and Profitability
Ethos’s earnings growth is marked by steady increases in revenue, EBITDA, and net profits. The reported figures for Q3 FY25 and H1 FY25 are evidence of the company's ability to deliver strong performance, even in the face of external economic challenges. The scalability of its business model, along with earnings improvement driven by store expansions and digital integration, indicates a promising avenue for continued profitability. Investors view the company’s healthy margins as a reflection of operational efficiency combined with strong brand equity.
Integration of Offline and Online Strategies
A key component of Ethos’s resilience lies in its successful integration of offline and online sales channels. While the traditional brick-and-mortar model remains central to its operations, investments in e-commerce have opened up new revenue streams. This hybrid approach allows the company to mitigate risks associated with market disruptions in either channel. Furthermore, technological innovations in CRM systems, advanced order management, and digital marketing have further bolstered its competitive positioning, ensuring its market leadership is maintained even as consumer behavior evolves.
Conclusion
In conclusion, Ethos India Ltd stands out as a formidable force in the luxury retail space in India. Its robust financial performance, aggressive market expansion, and proactive diversification strategies have carved a distinctive niche within a competitive market, positioning the company for long-term success. The company’s strategy to integrate digital transformation with its established offline presence has not only enhanced its revenue streams but also provided a cushion against various economic and competitive risks.
Although the business is subject to certain risks—such as currency volatility, intensifying competition, and supply chain complexities—these challenges are largely mitigated by the company’s strategic initiatives and operational efficiencies. A consistent upward trend in financial metrics, reaffirmed by multiple analyst ratings and target share prices, underscores Ethos’s potential for sustained growth. Additionally, its focused approach in expanding into broader luxury categories positions Ethos advantageously against market shifts and consumer trends.
To summarize, Ethos India Ltd is not only a leader in the premium and luxury watch segment but also an innovator in leveraging technology and diversification to secure future growth. Investors and industry watchers alike should monitor the company’s expansion initiatives closely. Continued store openings, digital advancements, and product diversification serve as strong indicators that Ethos is well-equipped to handle both current market fluctuations and future opportunities.
References
- Ethos Ltd Research Report - Trendlyne
- Ethos India Ltd Q3 FY25 Results - MyDhanush
-
ICICI Direct Equity Rapid Results for Ethos
- Economic Times Stock Report on Ethos Ltd
- NDTV Profit Research Report on Ethos Q1
Recommended Related Queries
 images.moneycontrol.com
 images.assettype.com
Last updated February 21, 2025