
Navigating Tough Financial Conversations
Essential FAQs and Strategies for Couples and Young Professionals
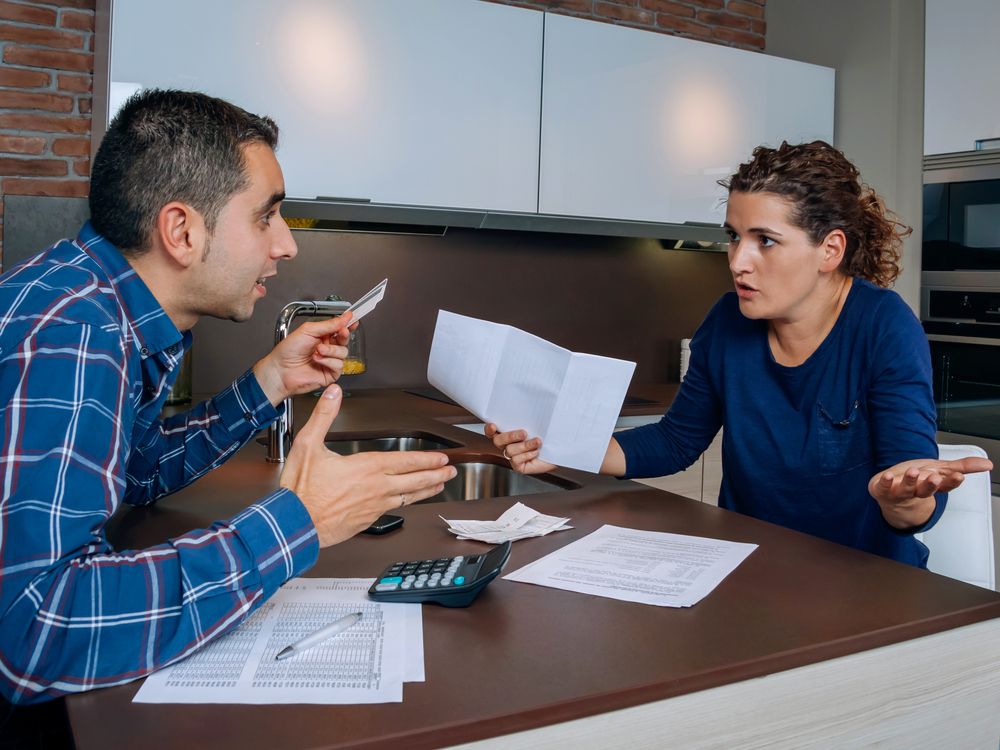
Key Highlights
- Trust Building: Open financial dialogues lay the foundation for trust and long-term financial security.
- Effective Communication: Using empathy, active listening, and regular check-ins ensures that challenging topics lead to mutual understanding.
- Comprehensive Financial Planning: Detailed discussion of income, expenses, debts, and future goals contributes to a shared financial vision.
Introduction
Discussing finances can be a sensitive and sometimes stressful topic for both couples and young professionals. However, clear and empathetic financial conversations are a cornerstone of building a strong relationship and ensuring long-term financial stability. In this comprehensive guide, we outline frequently asked questions (FAQs) and elaborate on effective strategies that help navigate tough financial conversations. Whether you're discussing budget planning with your partner or trying to get a grasp on personal finance as a young professional, the insights presented here will empower you to take control of your financial future with confidence.
FAQs on Navigating Tough Financial Conversations
1. Why Are Financial Conversations Important in Relationships?
Financial conversations offer a multitude of benefits that significantly impact the overall health of a relationship. They are vital for:
- Building Trust: Regular and open discussions about finances eliminate surprise expenses, reducing the potential for mistrust between partners.
- Preventing Conflict: Misunderstandings relating to income, spending, or debt can be major sources of conflict. Transparent conversations help resolve potential issues before they escalate.
- Aligning Goals: These discussions enable couples to work towards joint financial goals such as purchasing a home, planning for retirement, or saving for a major expense.
- Enhancing Stability: By addressing financial concerns collectively, couples can face economic challenges head-on, leading to improved financial security.
2. How Should Couples Initiate a Financial Conversation?
Initiating a financial conversation requires careful planning and consideration. A successful start can set the tone for a constructive dialogue. Here are recommended strategies:
Choose the Right Time and Place
Select a time when both partners are calm and free from distractions. Avoid initiating these discussions during stressful moments or when either party feels rushed. A neutral and quiet setting, such as a cozy living room or a quiet café, may provide the ideal atmosphere.
Plan an Agenda
Outline the topics to discuss before initiating the conversation. Prior topics might include income, expenses, debts, and goals. Having a clear agenda helps keep the discussion focused and prevents it from deviating into emotionally charged territory.
Frame the Discussion Positively
Start by expressing a common interest in strengthening your financial situation rather than highlighting disagreements. Begin with positive aspects, such as being proud of what you have saved so far, before addressing challenges. This approach fosters cooperation and reduces defensiveness.
3. What Are the Essential Topics to Cover?
A broad range of financial subjects should be discussed to ensure that both partners understand the full picture and can plan accordingly. Critical topics include:
Income and Expenses
Discuss your individual and combined incomes, current expenses, and budgeting practices. Transparency about what comes in and what goes out is fundamental for effective planning.
Debt and Credit Histories
Review any outstanding debts such as student loans, credit card balances, or other financial obligations. An open and honest discussion about your credit history and credit scores can highlight potential obstacles and opportunities for improvement.
Savings, Investments, and Retirement Goals
Share your perspectives on savings plans, your current investment portfolios, and your visions for retirement. Establishing both short-term and long-term financial goals ensures that each partner is on the same page.
Spending Habits and Values
Explore your spending behaviors and the influences behind them. Understanding whether each partner tends to be a saver or a spender will help in creating balanced financial strategies.
4. How Do You Avoid Resentment During Financial Discussions?
Resentments can build when financial discussions become entangled with emotions. To avoid such issues, follow these guidelines:
- Use "I" Statements: Communicate your feelings and concerns without placing blame. For example, say "I feel worried when we do not plan our budget" instead of "You never help with budgeting."
- Practice Active Listening: Ensure that each partner has a chance to express their thoughts without interruption. Reflect back what you hear and validate their opinions.
- Avoid Criticism: Keep the conversation focused on facts and shared goals rather than personal shortcomings. Emphasize finding solutions together.
- Take Responsibility: Acknowledge your role in past financial decisions or missteps. Admitting errors helps both partners move forward constructively.
5. What Strategies Can Young Professionals Employ for Financial Success?
Young professionals face unique challenges balancing ambition and financial responsibility. Below are practical strategies to help manage finances effectively:
Budgeting and Expense Management
Create a detailed budget that accounts for both fixed expenses and variable costs. Utilizing digital budgeting tools and apps can assist in tracking spending and maintaining financial discipline.
Building an Emergency Fund
Prioritize establishing an emergency fund that covers at least three to six months of living expenses. This safety net can prevent financial stress in case of unexpected circumstances.
Investing Early
Start investing as early as possible to harness the power of compound interest. Even small, regular contributions to retirement accounts or other investment vehicles can lead to significant growth over time.
Seeking Professional Guidance
When necessary, young professionals should not hesitate to seek assistance from fee-only financial advisors. Professional advice can provide tailored strategies that best suit individual financial situations.
6. What Are Some Techniques for Managing Conflict During Financial Conversations?
Financial disagreements can be managed effectively by employing techniques that focus on resolution and mutual understanding:
- Focus on Common Goals: Redirect the conversation to mutual financial aspirations rather than dwelling on differences.
- Schedule Regular Check-Ins: Regular financial discussions can help catch potential disagreements early before they develop into larger issues.
- Consider Mediation: If conflicts persist, involving a financial counselor or mediator can help provide an impartial perspective and aid in resolving disputes.
- Take Breaks if Necessary: When the conversation becomes too heated, agree to take a short break and resume once emotions have cooled down.
7. When Should Professional Financial Help Be Sought?
It is advisable to seek guidance from financial professionals when financial conversations begin to feel overwhelming or when complex financial decisions are at hand. Some scenarios include:
- Persistent Disagreements: If you repeatedly struggle to agree on financial matters, particularly on issues like debt management or budgeting, an advisor’s insight can be invaluable.
- Complex Financial Goals: Making significant investments, planning for retirement, or navigating separation of finances may benefit from the expertise of a professional.
- Objective Mediation: Sometimes, both partners may need an unbiased perspective to help structure the conversation constructively and prevent emotional escalation.
Practical Tools and Techniques
Beyond discussion and agreement, several practical tools can assist both couples and young professionals in managing their financial conversations and overall financial plans. Implementing these techniques can result in a more organized and actionable financial road map.
Creating a Comprehensive Financial Table
A structured table that organizes your financial information is one of the simplest yet most effective tools available. Use the table below as a guide for setting up your own financial plan, which may include key sections like income, expenses, debts, and savings goals.
| Category | Details | Goals/Notes |
|---|---|---|
| Income | Salary, bonuses, and any additional sources | Target: Increase by 5% annually |
| Expenses | Rent/mortgage, utilities, groceries, entertainment | Goal: Allocate a fixed percentage and identify reductions |
| Debts | Credit cards, student loans, car loans | Plan: Prioritize high-interest debt repayments |
| Savings & Investments | Emergency fund, retirement accounts, stocks, bonds | Objective: Contribute regularly and optimize portfolio |
| Financial Goals | Buying a home, vacations, educational expenses | Plan: Set measurable timelines and review progress quarterly |
Leveraging Digital Tools
Modern technology offers a variety of digital tools to support financial management:
- Budgeting Apps: Many apps can link your bank accounts and automatically classify transactions, making budgeting easier.
- Financial Planning Software: Programs that help visualize your goals and forecast financial outcomes provide clarity for planning discussions.
- Online Courses: Web-based courses offer structured learning on personal finance topics, essential for improving financial literacy.
Expert Tips for a Successful Financial Conversation
For both couples and young professionals, expert tips can facilitate productive financial exchanges:
Focus on Transparency and Honesty
Honesty lays the groundwork for effective communication. Both partners should fully disclose their financial statuses, including hidden debts or unplanned expenditures. Transparency not only builds trust but also ensures that both parties are fully informed when planning their future together.
Use Empathy as a Core Strategy
Recognize that financial issues often carry emotional baggage. Understand that both you and your partner may have different histories and attitudes towards money. Incorporate empathy in your conversation by acknowledging these differences and grounding your approach in mutual understanding.
Schedule Regular Financial Check-Ins
Establishing a routine for financial discussions prevents issues from piling up. Whether it’s a monthly review of your budget or a quarterly meeting to reassess goals, consistent communication ensures that both partners remain aligned. This proactive approach can prevent crises and encourage continual progress towards shared objectives.
Educate and Empower Yourself
Both individuals in a relationship should invest in their own financial literacy. Read books, attend workshops, and subscribe to trusted financial advice channels. The more knowledge you have, the better equipped you will be to tackle financial challenges collaboratively.
Additional Considerations for Couples and Young Professionals
In addition to initiating and engaging in financial conversations, here are further considerations that may help enhance your financial planning:
Personal Financial Histories
Both partners often have different backgrounds, which can influence spending habits and financial decision-making. It is beneficial to discuss past experiences and how they affect current attitudes toward money. Recognizing these differences can help in understanding each other’s perspectives and laying out a path forward that respects each individual’s history.
Financial Values and Priorities
Couples should articulate what values are most important to them when it comes to money. Is it security, wealth accumulation, generosity, or achieving personal dreams? Aligning your values can greatly improve your approach to dealing with financial issues and ensure that decisions made are reflective of mutual priorities.
Conflict Resolution Techniques
When disagreements do occur, utilizing specific conflict resolution techniques can maintain the conversation’s productivity:
- Start by listing areas of agreement before moving on to disagreements.
- Agree to take periodic breaks if conversations become emotionally intense.
- Revisit topics once both parties have had time to reflect.
- Consider third-party mediation if conflicts persist over extended periods.
Balancing Short-Term Needs and Long-Term Goals
Financial planning often requires balancing immediate expenses with long-term objectives like retirement planning or buying a home. Discuss these aspects openly to ensure that short-term sacrifices align with long-term aspirations. This balancing act is key to creating a sustainable financial plan that accommodates both present and future needs.
Practical Case Scenarios
The following scenarios illustrate common financial conversations and how they can be approached constructively:
Scenario 1: Budgeting as a Team
A couple decides to set a monthly budget after noticing that unplanned expenses have been reducing their savings. They begin by listing all sources of income and classifying monthly expenses into fixed costs (rent, utilities) and variable costs (dining, entertainment). Using a shared spreadsheet, they agree on a percentage of income to allocate for discretionary spending, while also setting savings targets. Regular monthly check-ins help them adjust their budget based on changes in income or unexpected expenses.
Scenario 2: Navigating Debt Management
A young professional, overwhelmed by student loans and credit card debt, initiates a conversation with their partner about long-term financial strategies. Together, they review all outstanding debts, discuss their respective interest rates, and prioritize debt repayment. They decide to consolidate high-interest debts and set up automated payments to ensure consistency. Continuous monitoring of progress provides motivation and accountability, easing anxiety related to the debt.
Scenario 3: Investment Planning and Future Security
A couple in their early 30s, mindful of building a secure financial future, decide to begin investing together. Despite some initial disagreements about risk tolerance and investment options, they agree to consult a dedicated financial advisor. They educate themselves on market trends and opt for a diversified portfolio that balances stocks, bonds, and other assets. Their shared commitment to periodic reviews ensures that their investment strategy evolves in step with market conditions and lifestyle changes.
Technology and Mixed Financial Approaches
In today's digital age, technology plays a vital role in supporting financial conversations. Couples and young professionals can leverage various apps and online platforms to facilitate transparent discussions and effective money management.
Digital Financial Management Tools
Financial management apps available on smartphones not only track spending but also offer features such as automated categorization, alerts on overspending, and budgeting templates. These tools provide both partners with real-time insights into their financial health.
Online Learning and Resources
Continuous education in personal finance remains essential. Taking advantage of online courses, webinars, and workshops can enhance financial literacy. Many platforms offer interactive modules that break down complex topics such as investments, retirement planning, and credit management into digestible segments.
Additional Financial Literacy Tips for Young Professionals
Improving financial literacy is a lifelong endeavor that starts with acknowledging the complexity of managing finances. For young professionals, gaining control over their financial future can be achieved by:
- Structured Learning: Enroll in personal finance classes that cover budgeting, investing, and debt management.
- Utilizing Financial Advisors: When personal research reaches its limits, reaching out to a financial advisor can provide clarity and direction.
- Engaging with Financial Communities: Participating in community forums or discussion groups can expose you to diverse perspectives and success stories.
- Instilling Financial Discipline Early: Regular savings, controlled spending, and a focus on long-term investments are practices that provide a strong financial foundation.
The Role of Preparation in Successful Financial Dialogues
Being well-prepared for financial conversations not only reduces anxiety but also increases the likelihood of a successful and constructive exchange. Preparation involves collecting all relevant financial documents, understanding both personal and shared financial histories, and defining future financial targets. Doing so allows the conversation to move beyond concerns into actionable steps and mutually agreed upon strategies.
Practical Preparatory Steps
To ensure conversations are productive, consider these preparatory steps:
- Gather past financial statements, bills, and receipts to have a clear understanding of your current financial state.
- Establish individual financial priorities and understand the reasons behind them.
- Write down questions or topics you want to discuss, ensuring nothing crucial gets overlooked.
- Agree on a timeline for reviewing financial progress and adjusting plans as necessary.
References
- Tips for Successful Financial Conversations with Your Partner - Alpha Wealth Funds
- Financial Conversations for Couples - FMI Financial
- How to Discuss Finances Without Causing Resentment - Gabriele Hilberg
-
Money Talk for Couples: How to Discuss Finances - Couples Counseling Now
- Communication Tips for Couples - Fidelity
- Effective Strategies for Financial Communication for Couples - Berkshire MM
- 6 Money Conversations to Have in Your Marriage - Principal
- Financial Planning for Young Adults - Empower
- Eight Tips for Young Investors - Investopedia
- How to Talk with Your Partner About Money - CNBC
Recommended Queries for Deeper Insights
Last updated March 1, 2025