
Unraveling "Ang. 9, Tz. 5": A Deep Dive into German Reorganization Tax Law
Deciphering a pivotal reference in Germany's leading UmwStG commentary for complex corporate restructuring.
Key Insights into the UmwStG Commentary
- Authoritative Standard Work: The commentary by Rödder, Herlinghaus, and van Lishaut is universally recognized as the definitive reference for German reorganization tax law (UmwStG), offering in-depth analysis and practical guidance for complex corporate restructurings.
- "Ang. 9, Tz. 5" Deciphered: This specific citation refers to "Appendix 9 (Anhang 9)" and "marginal note (Randnummer/Textziffer) 5" within the commentary, indicating a precise location for detailed explanations of specific tax issues related to reorganizations.
- Comprehensive Coverage and Practical Relevance: The commentary extends beyond the direct scope of the UmwStG, covering related tax areas, EU law, and recent jurisprudence, making it indispensable for professionals navigating intricate tax implications of mergers, spin-offs, and other corporate transformations.
The citation "Rödder/Herlinghaus/van Lishaut, Kommentar zum UmwStG, Ang. 9, Tz. 5" directs one to a highly specific and significant passage within one of Germany's most authoritative legal commentaries. This commentary, authored by leading experts Thomas Rödder, Andreas Herlinghaus, and Ingo van Lishaut, is considered the benchmark for understanding the complex landscape of the German Reorganization Tax Act (Umwandlungssteuergesetz, UmwStG). Its reputation as a "standard work for upper-class restructurings" underscores its critical role for practitioners, academics, and legal professionals alike.
Deconstructing the Citation: "Ang. 9, Tz. 5"
To fully grasp the implication of this citation, it's essential to break down its components:
- Rödder/Herlinghaus/van Lishaut: These are the esteemed authors and editors of the commentary. Thomas Rödder is a certified public accountant/tax consultant and honorary professor. Andreas Herlinghaus is a judge at the Federal Fiscal Court (Bundesfinanzhof) and managing director of the Institute for Tax Law at the University of Bonn. Ingo van Lishaut is a senior ministerial councilor and head of the income tax group in the Ministry of Finance of North Rhine-Westphalia, specializing in international tax law. In recent editions, Christian Graw and Peter Heinemann have joined as additional editors/authors.
- Kommentar zum UmwStG: This signifies that the work is a comprehensive commentary on the German Reorganization Tax Act. The UmwStG governs the tax implications of various corporate restructuring processes, including mergers (Verschmelzung), spin-offs (Spaltung), changes of legal form (Formwechsel), and contributions (Einbringung) of assets or businesses into corporations or partnerships.
- Ang. 9: This abbreviation stands for "Anhang 9," which translates to "Appendix 9." The commentary includes numerous appendices (typically 16) that extend beyond the direct articles of the UmwStG itself. These appendices are crucial for addressing complex practical questions and interconnections with other relevant tax areas, such as income tax (EStG), corporate income tax (KStG), inheritance tax, gift tax, and international tax law. They provide a holistic view of the tax landscape surrounding reorganizations.
- Tz. 5: This stands for "Textziffer" or "Randnummer," meaning "marginal note" or "paragraph number" 5. This specifies the exact paragraph or section within Appendix 9 where the relevant information is located. These marginal notes provide precise, detailed explanations, interpretations, examples, or analyses of case law pertinent to a specific point.
The Significance of the Rödder/Herlinghaus/van Lishaut Commentary
This commentary is lauded for its depth, precision, and practical relevance. It is not merely a summary of the law but an exhaustive analysis that delves into the nuances of reorganization tax law. Key aspects that highlight its significance include:
Comprehensive Scope and Expertise
The commentary covers all major types of reorganizations, from mergers and spin-offs to changes in legal form and contributions. It provides detailed discussions on crucial topics such as contributions to corporations under § 20 UmwStG, a section often spanning over 200 pages due to its complexity. The authors' blend of academic rigor and practical experience (as a tax consultant, judge, and finance ministry official) ensures that the commentary offers both theoretical clarity and actionable advice.
Practical Guidance and Examples
Written by practitioners for practitioners, the work is replete with numerous examples that illustrate the application of challenging and intricate subject matter. This practical approach makes it an invaluable tool for tax advisors, legal professionals, and corporate decision-makers involved in conceiving, implementing, or managing crises in complex transactions.
Integration of EU Law and Jurisprudence
The commentary consistently considers the broader legal framework, including EU law, the principle of "Union loyalty" (AEUV), and the tax merger directive. It integrates recent European Court of Justice (EuGH) case law, ensuring that readers are abreast of international legal developments impacting German reorganization tax law.
Updates and Editions
The commentary is regularly updated to incorporate legal changes and new jurisprudence. The 3rd edition, published in 2019 (ISBN 978-3-504-37014-5), laid the groundwork, while the 4th edition, released in 2025 (ISBN 978-3-504-37026-8), further refines the content. The 4th edition includes a new appendix specifically addressing § 50i EStG constellations in reorganizations and incorporates developments in mergers, spin-offs, contributions, and cross-border situations.
Potential Content of Appendix 9, Marginal Note 5
While the precise content of "Ang. 9, Tz. 5" is not explicitly provided, based on the general structure and focus of the commentary's appendices, it likely addresses a specialized tax detail or a cross-connection to related tax law provisions within the context of the UmwStG. It could cover topics such as:
- Tax implications of specific reorganization cases: This might involve the treatment of tax loss carryforwards, interest carryforwards, or other fiscal benefits in the context of reorganizations, potentially referencing § 4h EStG.
- Transfer balance sheet issues: Detailed rules regarding the valuation and accounting aspects of assets and liabilities during a reorganization, especially concerning their tax basis.
- Inland or cross-border contribution provisions: Specific conditions or effects related to tax neutrality for contributions, including the interaction with other tax laws like the Income Tax Act (EStG), Corporate Income Tax Act (KStG), or Real Estate Transfer Tax Act (GrEStG).
- Conditions for tax neutrality: Precise requirements for achieving tax-neutrality in certain reorganization types, including application procedures or consequences of waiving certain tax elections.
- Disputed or highly practical interpretation questions: Analysis of specific statutory text provisions that are frequently debated or hold significant practical relevance for tax professionals. This could include scenarios involving the conversion of a corporation into a partnership and its tax consequences.
For instance, if "Ang. 9" pertains to a specific aspect of "Formwechsel" (change of legal form) from a corporation to a partnership, "Tz. 5" might elaborate on the nuanced tax consequences, such as the potential loss of interest carryforwards (§ 4h Abs. 1 Satz 2 EStG) or the offsetting of transfer gains, often linking to relevant Federal Fiscal Court (BFH) rulings.
This radar chart illustrates the perceived strength of the Rödder/Herlinghaus/van Lishaut commentary across various critical dimensions of tax law analysis. The outer perimeter signifies higher strength or comprehensiveness in that particular area. "Depth of Analysis" highlights its detailed explanations, while "Practical Examples" emphasizes its utility for practitioners. "Integration of EU Law" points to its cross-border relevance, and "Up-to-date Content" reflects its commitment to incorporating recent legal changes. "Coverage of UmwStG Articles" indicates its thoroughness within the core act, and "Appendices & Related Tax Areas" shows its broad reach into other tax laws. This chart demonstrates the commentary's holistic approach and high value as a resource.
Navigating Complex Reorganizations: A Mindmap of Key Considerations
and Case Analysis"] id10["Key Features"] id11["Authoritative & Standard Work"] id12["Practical Focus & Examples"] id13["Integration of EU Law & EuGH Cases"] id14["Regular Updates (4th Ed. 2025)"] id15["Reorganization Types Covered"] id16["Mergers (Verschmelzung)"] id17["Spin-offs (Spaltung)"] id18["Changes of Legal Form (Formwechsel)"] id19["Contributions (Einbringung)"] id20["Related Tax Areas (covered in Appendices)"] id21["Income Tax (EStG)"] id22["Corporate Income Tax (KStG)"] id23["Real Estate Transfer Tax (GrEStG)"] id24["International Tax Law"]
This mindmap visually organizes the key components and areas of expertise covered by the Rödder/Herlinghaus/van Lishaut commentary on German Reorganization Tax Law. It highlights the structured nature of the commentary, from its main articles and appendices to the detailed marginal notes. The mindmap also illustrates the various types of reorganizations addressed and the crucial related tax areas that the commentary integrates, providing a comprehensive overview of its scope and utility.
Understanding Reorganization Tax Implications
The field of reorganization tax law is exceptionally intricate, requiring deep legal and tax expertise. A practical example of a complex issue addressed by such commentaries is the carryover of losses in corporate reorganizations. The following video offers an insightful look into this topic:
This video discusses the carryover of trade losses from a corporation to a partnership, a topic often explored in commentaries like Rödder/Herlinghaus/van Lishaut. It provides practical insights into how previous tax losses might be impacted during a change of legal form, which aligns with the kind of detailed tax consequences potentially analyzed in "Ang. 9, Tz. 5" within the UmwStG commentary, particularly concerning form changes or business asset transfers.
The intricate nature of German tax law, especially concerning corporate reorganizations, often leads to situations where the carryover of tax benefits, such as interest carryforwards or loss carryforwards, becomes a critical point of contention. The commentary, through sections like Appendix 9, Marginal Note 5, would likely dissect specific scenarios and their tax outcomes. For example, a change of legal form from a corporation to a partnership can have significant implications for the continuity of certain tax advantages. The commentary would offer authoritative interpretations and practical solutions, considering not only the direct text of the UmwStG but also its interplay with other tax laws like the EStG and the latest court decisions.
Overview of Key Editions and ISBNs
For those seeking to consult the commentary, understanding the different editions and their respective ISBNs is helpful:
| Edition | Year of Publication | ISBN | Key Authors/Editors | Notes |
|---|---|---|---|---|
| 3rd Edition | 2019 | 978-3-504-37014-5 | Rödder, Herlinghaus, van Lishaut | Standard edition, widely recognized for its comprehensive coverage. Includes 16 appendices. |
| 4th Edition | 2025 | 978-3-504-37026-8 | Rödder, Herlinghaus, Graw, Heinemann | Updated to incorporate recent legal changes and jurisprudence, including new appendix for § 50i EStG constellations. |
This table provides a concise overview of the key editions of the Rödder/Herlinghaus/van Lishaut commentary, highlighting their publication years, ISBNs, and notable features. This information is crucial for pinpointing the exact version of the commentary and its specific content.
Illustrating Related Tax Scenarios
Complex tax issues in corporate reorganizations often involve the transfer of assets or changes in business structure, impacting various tax categories. The images below depict scenarios that could necessitate consulting specialized tax commentaries like Rödder/Herlinghaus/van Lishaut.
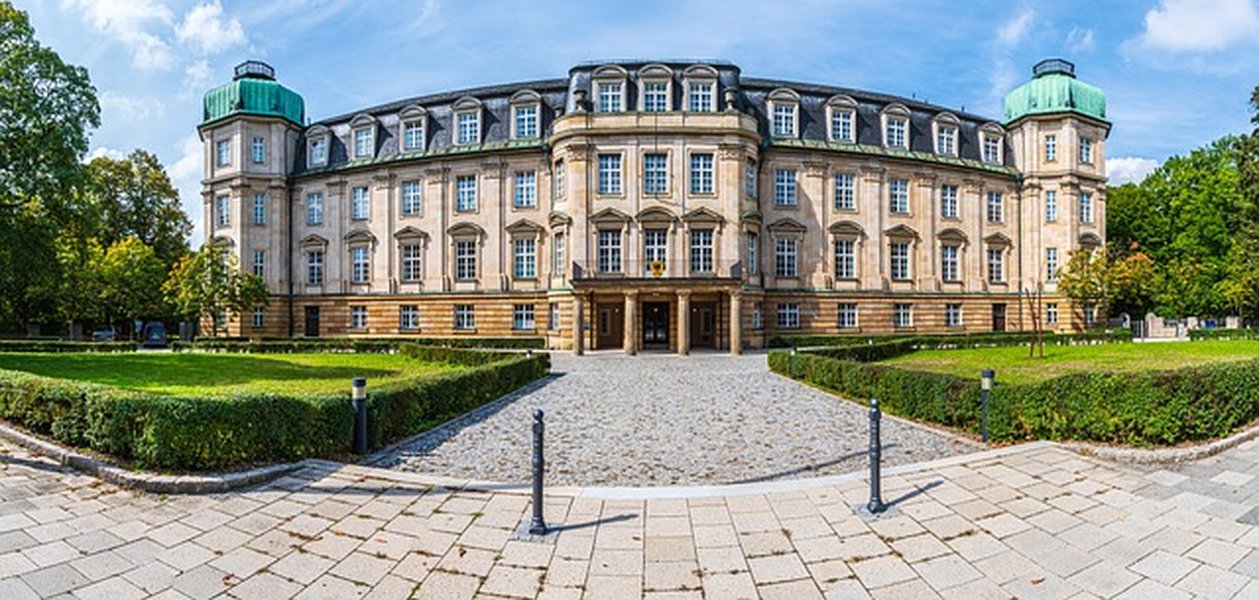
The Federal Fiscal Court (Bundesfinanzhof), whose rulings are often analyzed and incorporated into the commentary.
The commentary often refers to judgments from the Federal Fiscal Court (BFH), which is the highest court for tax matters in Germany. These judgments shape the interpretation and application of tax laws, and the commentary provides detailed analysis of their implications for reorganizations. For example, rulings on the limitation of trade tax pitfalls for new business assets during reorganizations are crucial for tax planning.

Financial considerations, such as the transition of business losses from a corporation to a partnership, are key aspects of reorganization tax law.
The image above highlights financial elements pertinent to tax law, specifically the transfer of business losses during a change from a corporation to a partnership. This type of transaction is a core area of focus within the UmwStG and is extensively discussed in the Rödder/Herlinghaus/van Lishaut commentary, particularly concerning the impact on tax-deductible items.
New business formations or the entry of new partners, which can trigger complex tax implications under the UmwStG.
This image depicts a business setup, relevant to discussions on the admission of new partners or changes in corporate structure. The commentary would cover the tax implications of such events, including contributions made by new partners, which are fundamental to the UmwStG's scope.
The economic value and tax considerations during asset contributions or share exchanges in reorganizations.
The image of a wallet symbolizes the financial valuation and tax implications arising from asset contributions or share exchanges, which are central to sections like § 20 UmwStG. The commentary provides guidance on differing valuation approaches and their tax consequences in reorganization contexts.
Frequently Asked Questions (FAQ)
What does "UmwStG" stand for?
Who are Rödder, Herlinghaus, and van Lishaut?
Why is "Ang. 9, Tz. 5" important?
What kind of content might be found in Appendix 9, Marginal Note 5?
How frequently is the commentary updated?
Conclusion
The reference "Rödder/Herlinghaus/van Lishaut, Kommentar zum UmwStG, Ang. 9, Tz. 5" points to a highly specialized and authoritative source within German tax law. It signifies a deep dive into specific intricacies of corporate reorganization tax, likely concerning an issue addressed in Appendix 9 of this seminal commentary, with detailed analysis provided in marginal note 5. For professionals navigating the complex landscape of German corporate restructurings, this commentary serves as an indispensable guide, offering unparalleled depth, practical examples, and current legal insights, ensuring advisory certainty in even the most challenging transactions.
Recommended Further Queries
- Tax consequences of corporate form changes in Germany
- Impact of § 20 UmwStG on business contributions
- Interaction of UmwStG with EU Merger Directive
- Analysis of tax loss carryforwards in German reorganizations
Referenced Search Results
 cdn-assetservice.ecom-api.beck-shop.de
