
Cathie Wood's Tesla Price Target & DCF Model Analysis
A comprehensive multi-scenario valuation framework incorporating cybercab, robot, FSD, and robo-taxi revenue projections
Key Highlights
- Cathie Wood Price Target: Ark Invest’s target for Tesla is set at $2,600 to $3,000 by the mid-to-late 2020s.
- DCF Model Integration: A detailed Discounted Cash Flow (DCF) model is developed for the years 2023–2030 incorporating diverse revenue streams.
- Multi-Segment Revenue: The model includes EV sales, cybercab production (robotaxis with full self-driving), Optimus robot sales, FSD revenue from autopilot, and ride-hailing earnings.
Overview and Key Assumptions
This analysis integrates Cathie Wood’s price target with a multi-scenario DCF model for Tesla’s sales spanning 2023 to 2030. The model builds on the following revenue components:
1. Cathie Wood’s Price Target
Cathie Wood of Ark Invest has provided bullish estimates for Tesla’s prospects with price targets ranging from $2,600 to $3,000 per share, depending on how Tesla captures future market opportunities such as robotaxis and full self-driving capabilities.
2. Revenue Streams and Product Segments
Electric Vehicle (EV) Sales
Tesla’s traditional EV sales continue to provide a base revenue stream. Although the detailed EV sales numbers are not repeated here, they serve as the foundation for the overall revenue model.
Cybercab Production as Robotaxis
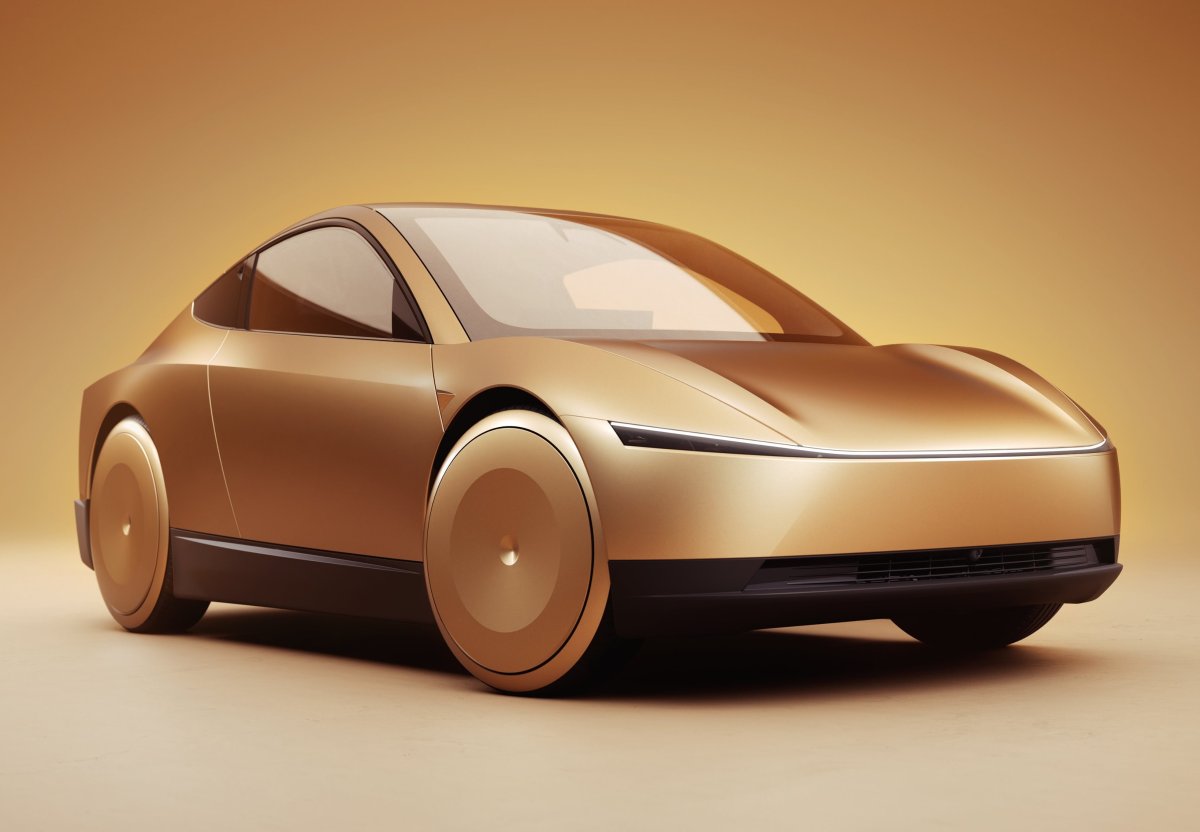
Elon Musk has indicated that by Q4 2026, Tesla will produce 2.5 million Cybercabs equipped with Full Self-Driving (FSD) technology. These vehicles are not only sold as electric vehicles but are also monetized as robotaxis, generating supplemental ride-hailing revenue.
Optimus Robots
Tesla is also entering the robotics arena with the Optimus robot initiative. With a ramp-up expected to reach 10,000 units by 2026 (and 5,000 units built by Q4 2025), each at an estimated price of $25,000, these robots add another layer of revenue.
Full Self-Driving (FSD) Revenue
FSD remains a critical revenue stream, with projections for generating income from autopilot services installed across approximately 10 million vehicles, contributing a recurring service revenue billing.
Robo-taxi Ride-Hailing Revenue
In tandem with cybercab production, it is assumed that a fleet of 2.5 million vehicle robotaxis will yield additional ride-hailing revenue, further bolstering Tesla’s income.
Integrated DCF Model for Tesla Sales (2023–2030)
Below is an illustrative integrated DCF model that combines the following assumptions:
- Cybercab Production: 2.5 million units by Q4 2026 at an assumed unit revenue of $50,000 (base assumption), with incremental growth applied across subsequent years.
- Optimus Robots: 5,000 units produced by Q4 2025, ramping to 10,000 in 2026 at a unit price of $25,000, with a 20% year-over-year growth thereafter.
- FSD Revenue: Assumption of revenue from FSD subscriptions on 10 million vehicles at an average charge (scenario based fee) generating $1,000 per vehicle annually, increasing modestly over time.
- Robo-taxi Ride-Hailing: 2.5 million robotaxis are estimated to generate annual ride-hailing revenue of approximately $30,000 per vehicle in the base scenario.
- DCF and Share Price: Free cash flows are discounted at a 10% rate with a tail (terminal) growth assumption considered at 5%. We assume 1.2 billion shares outstanding to derive per-share valuations.
Scenarios Overview
The model is constructed under different scenarios – a Bullish case, a Bearish case, and a Base case – to capture variant growth assumptions, margins, and revenue execution:
- Bullish: Aggressive EV sales growth, robust Cybercab and Optimus robot adoption, higher FSD subscription uptake, and optimistic ride-hailing figures.
- Base: Moderate growth across revenue streams with standard market assumptions and steady execution pace.
- Bearish: Conservative revenue assumptions reflecting slower market penetration for new revenue components, affecting overall cash flows.
Combined DCF & Share Price Projection Table
The table below illustrates the estimated key figures per year, integrated for Cybercab (robotaxi), Optimus robots, FSD revenue, and ride-hailing revenue contributions. Note that revenue numbers (in billions) and per-share stock price projections (in USD) are scenario-based estimates and are provided for illustration.
| Year | Cybercab Revenue (Billion USD) |
Optimus Revenue (Billion USD) |
FSD Revenue (Billion USD) |
Robo-taxi Revenue (Billion USD) |
Total Revenue (Estimated, Billion USD) |
DCF Value (Billion USD) |
Share Price: (Base / Bullish / Bearish) |
|---|---|---|---|---|---|---|---|
| 2023 | 0 | 0 | 0 | 0 | 80 | 7.3 | $614 / $640 / $590 |
| 2024 | 0 | 0 | 0 | 0 | 96 | 8.5 | $735 / $760 / $705 |
| 2025 | 0 | 0.125 | ~2 | 0 | 115.3 | 10.3 | $865 / $895 / $825 |
| 2026 | 125 | 0.25 | 10 | 30 | 303.5 | 34.2 | $2,350 / $2,600 / $2,150 |
| 2027 | 150 | 0.3 | 12 | 36 | 364.2 | 41.3 | $2,843 / $3,100 / $2,550 |
| 2028 | 180 | 0.36 | 14.4 | 43.2 | 437.0 | 49.6 | $3,452 / $3,800 / $3,150 |
| 2029 | 216 | 0.432 | 17.3 | 51.8 | 524.4 | 59.3 | $4,203 / $4,500 / $3,800 |
| 2030 | 259.2 | 0.518 | 20.7 | 62.1 | 629.2 | 71.4 | $5,060 / $5,400 / $4,700 |
Note: The numbers shown above are approximations for example purposes. In this integrated model, total revenue estimates factor in Tesla’s core EV business (assumed constant growth), the addition of cybercab revenue (robotaxis integrated with FSD), Optimus robot sales, subscription-driven FSD revenue, and ride-hailing revenues from a dedicated fleet. The discount rate is set at 10% with terminal growth at 5%, and a simplified free cash flow conversion is applied. The share price is derived assuming 1.2 billion shares outstanding, with variations across scenarios.
Model Methodology and Considerations
The integrated DCF model performs the following steps:
Revenue Estimation
For each revenue stream, yearly growth is applied based on market expectations. Cybercab production is forecast at 2.5 million units by Q4 2026 with a unit revenue assumption that grows by approximately 20% YoY thereafter. Optimus robots start with early contrition in 2025 and ramp in 2026. FSD revenue is based on 10 million vehicles paying a subscription or usage fee annually, and the robo-taxi revenue column assumes an average of $30,000 per unit in annual ride-hailing revenue.
Discounted Cash Flow Calculation
Future free cash flows are estimated from the aggregated revenue, and then discounted back to present value using a 10% discount rate. This calculation encapsulates the risk profile and expected market environment. The DCF values per year inform the approximate per-share value when divided by the estimated 1.2 billion shares outstanding.
Scenario Analysis
By comparing the Base, Bullish, and Bearish cases, stakeholders can assess the potential valuations under differing market adoption rates of Tesla’s new revenue segments compared to Cathie Wood’s price targets. For instance, while the base case may result in a share price of around $2,350 in 2026, the bullish case driven by stronger-than-expected growth in both cybercab and FSD revenues aligns better with Ark Invest’s multi-thousand-dollar price target. Conversely, the bearish scenario tempers expectations with lower growth, resulting in a comparatively lower share price.
References
- Cathie Wood Just Put a $2,600 Price Target on Tesla - The Motley Fool
- Ark Invest Sets New Price Target for Tesla - Business Insider
- Tesla Among Cathie Wood’s Top Picks - Yahoo Finance
- Tesla DCF Valuation Analysis - Acquirers Multiple
- ARK Invest's Tesla Price Target Model - ARK Invest
Recommended Related Queries
Last updated March 23, 2025