
Unraveling the Global Financial Crisis: A Deep Dive into Its Origins
Understanding the Complex Interplay of Factors that Led to the 2008 Economic Meltdown
Key Insights into the Global Financial Crisis
- Subprime Mortgages and Housing Bubble: The crisis was primarily triggered by a massive housing bubble in the U.S., fueled by widespread predatory lending practices, particularly subprime mortgages. When this bubble burst, it initiated a domino effect across the global financial system.
- Interconnectedness and Deregulation: The global financial system's intricate connections meant that the U.S. housing market collapse quickly spread worldwide. This was exacerbated by a significant lack of regulation and oversight in the financial industry, allowing excessive risk-taking and the proliferation of complex, toxic financial instruments.
- Loose Monetary Policy and Speculation: A period of loose monetary policy, characterized by low interest rates and an ample money supply, encouraged excessive borrowing and speculative investment in assets, further inflating the housing bubble and increasing the financial system's vulnerability.
The Global Financial Crisis (GFC) of 2007-2009, also widely known as the Great Recession, stands as the most severe economic downturn since the Great Depression of the 1930s. Its origins are multifaceted, stemming from a complex interplay of financial innovations, regulatory failures, macroeconomic imbalances, and human behavior. While the immediate trigger was the collapse of the U.S. housing market, the underlying causes were deeply rooted in a system that encouraged excessive risk and lacked adequate oversight.
The Genesis of the Crisis: A Web of Interconnected Factors
The GFC was not a singular event but rather the culmination of several contributing factors that amplified each other, creating a systemic shock that reverberated across the globe. Understanding these individual components and their interactions is crucial to grasping the full scope of the crisis.
The Housing Market Bubble and Subprime Mortgages
At the heart of the crisis was the unprecedented U.S. housing bubble. For years leading up to 2007, housing prices soared, driven by easily accessible credit and speculative investment. A significant portion of this credit came in the form of "subprime mortgages" – loans extended to borrowers with poor credit histories and a high likelihood of default. Lenders, motivated by the prospect of quick profits from rising home values and the ability to package these loans into complex securities, relaxed their lending standards significantly. This predatory lending created an unsustainable market where many homeowners took on loans they could not afford.
When interest rates began to rise and housing prices started to fall in 2006-2007, the bubble burst. Homeowners with subprime mortgages, many of whom had adjustable-rate mortgages, found their monthly payments unaffordable, and the value of their homes plummeted below the mortgage amount. This led to a wave of foreclosures, saturating the market with distressed properties and further driving down prices.
The Role of Securitization and Derivatives
The issue was compounded by the financial innovation of securitization. Mortgage-backed securities (MBSs) were created by bundling thousands of individual mortgages, including subprime ones, into investment vehicles. These MBSs were then sold to investors worldwide. Financial institutions further sliced and re-packaged these MBSs into collateralized debt obligations (CDOs), often obscuring the underlying risk of the subprime loans within them. Credit rating agencies, often incentivized by the very institutions issuing these securities, frequently assigned high ratings to these risky instruments, misleading investors into believing they were safe.
Adding another layer of complexity were credit default swaps (CDSs). These were essentially insurance contracts against the default of debt instruments like MBSs and CDOs. As the housing market deteriorated, the value of these "toxic" securities plummeted, leading to massive losses for financial institutions that held them or had written CDSs on them. The interconnectedness of global financial institutions meant that the losses quickly spread, as institutions had large exposures to the U.S. housing market through these derivatives.
Regulatory Failures and Lack of Oversight
A critical factor contributing to the crisis was the significant lack of effective regulation and oversight of the financial industry. Deregulation, particularly the repeal of the Glass-Steagall Act in 1999 by the Gramm-Leach-Bliley Act, allowed commercial and investment banks to merge, increasing systemic risk. This led to a "shadow banking system" that operated outside traditional banking regulations, engaged in high-risk activities, and was largely opaque to regulators. The absence of robust oversight meant that financial institutions could engage in excessive risk-taking, maintain high levels of leverage, and create complex financial products without adequate scrutiny or capital requirements.
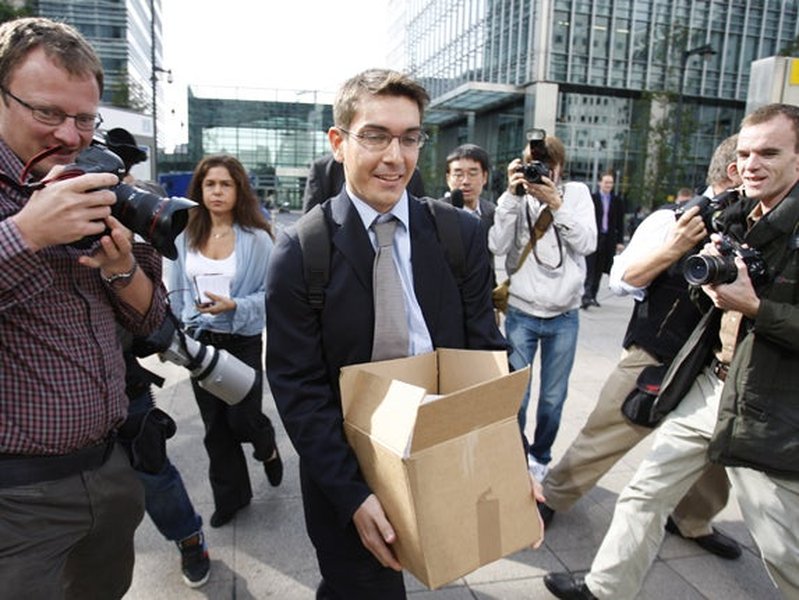
Lehman Brothers headquarters in Manhattan on September 15, 2008, the day of its collapse.
Loose Monetary Policy and Global Imbalances
The period leading up to the GFC was characterized by a prolonged era of loose monetary policy, particularly in the U.S., with low interest rates and an ample money supply. This environment made borrowing cheap and encouraged speculative investment in the housing market and other assets. While intended to stimulate economic activity, excessively loose monetary policy contributed to the formation of asset bubbles. Furthermore, global macroeconomic imbalances, such as large capital flows toward the United States from countries with high savings rates, contributed to the creation of asset bubbles that eventually burst.
Psychological Factors and Herd Behavior
Human behavior also played a significant role. During economic booms, over-exuberance and irrational optimism can lead to unsustainable speculation, a concept described as a "Minsky Moment." This euphoria encourages excessive borrowing and risk-taking. Conversely, during downturns, deep pessimism and herd-like investor behavior can accelerate the decline, as fear prompts a rapid sell-off of assets, further reducing liquidity and asset prices.
Visualizing the Contributing Factors: A Radar Chart Analysis
To better understand the relative impact and interconnectedness of the various factors contributing to the Global Financial Crisis, we can visualize them using a radar chart. This chart represents an opinionated analysis of how prominent each factor was in precipitating the crisis, based on expert consensus and historical accounts.
The radar chart visually emphasizes that the housing market bubble and subprime mortgages, coupled with inadequate regulation and the proliferation of complex financial instruments, were perceived to have the most significant impact on triggering the GFC. The chart also highlights the crucial role of interconnectedness and excessive leverage in spreading and amplifying the crisis.
The Global Ripple Effect: From U.S. Housing to Worldwide Crisis
What started as a crisis in the U.S. subprime mortgage sector quickly escalated into a global financial meltdown due to the intricate linkages within the international financial system. Investment banks and other financial institutions across Europe and Asia had heavily invested in U.S.-originated mortgage-backed securities and CDOs. When these assets lost value, these institutions faced massive write-downs, leading to a credit crunch and liquidity crisis worldwide.
The collapse of Lehman Brothers in September 2008 was a pivotal moment, triggering a widespread panic and freezing credit markets globally. This event underscored the systemic risk embedded in the financial system and prompted unprecedented government interventions, including bailouts and quantitative easing, to prevent a complete collapse of the international financial system.
Historical Parallels and Lessons Learned
Throughout history, economic crises and financial downturns have occurred due to various factors, from asset bubbles to geopolitical events. The 2008 GFC, while unique in its specifics, shares commonalities with previous crises, emphasizing the cyclical nature of economic activity and the importance of robust regulatory frameworks. Examining these historical events provides valuable context for understanding the causes and consequences of financial instability.
This video provides a concise history lesson on the events of the 2008 financial recession, explaining how it impacted global markets.
This video offers a succinct overview of the 2008 financial crisis, detailing the sequence of events that led to its global impact. It highlights how the collapse of major financial institutions and the freezing of credit markets resulted in significant declines in global indices. Understanding this timeline is crucial for comprehending the rapid and widespread nature of the crisis and the subsequent policy responses aimed at stabilization and recovery.
Comparing Financial Crises: A Brief Overview
While the 2008 Global Financial Crisis was particularly severe, it is one of many financial crises throughout history. Here's a brief comparison of some notable historical financial crises, highlighting their primary causes:
| Crisis Name | Period | Primary Causes | Key Characteristics |
|---|---|---|---|
| Tulip Mania | 1637 | Speculative bubble in tulip bulb prices. | First recorded speculative bubble; did not significantly harm the Dutch economy long-term but demonstrated market irrationality. |
| Credit Crisis of 1772 | 1772 | Overlending by Scottish banks, particularly the collapse of Ayr Bank. | Financial contagion spread to London; exacerbated political tensions leading to American Revolution. |
| The Great Depression | 1929–1939 | Stock market crash (1929), bank failures, drought, international trade collapse, flawed monetary policy. | Longest and most severe economic downturn in modern history; high unemployment, deflation, widespread poverty. |
| OPEC Oil Price Shock | 1973 | Oil embargo by OPEC against the U.S. and its allies. | Severe oil shortages, dramatic spike in oil prices, leading to stagflation (high inflation and stagnant growth). |
| Asian Financial Crisis | 1997 | Currency devaluation (Thai Baht), speculative attacks, inadequate financial regulation, unsustainable short-term foreign debt. | Affected several East Asian economies, led to widespread corporate defaults and IMF bailouts. |
| Global Financial Crisis (GFC) | 2007–2009 | U.S. housing bubble burst, subprime mortgages, securitization, derivatives, lack of regulation, excessive leverage. | Global credit crunch, major bank failures, significant government bailouts, triggered the Great Recession. |
Frequently Asked Questions (FAQ)
What is a recession?
How does a financial crisis differ from an economic recession?
What is a subprime mortgage?
What was the "Great Moderation" and how did it relate to the GFC?
Conclusion: A Systemic Breakdown
The Global Financial Crisis of 2008 was a monumental event driven by a complex web of factors. From the bursting of the U.S. housing bubble fueled by subprime mortgages and lax lending standards, to the proliferation of opaque and risky financial instruments, and the critical absence of robust regulatory oversight, the crisis exposed profound weaknesses in the global financial system. Loose monetary policy, global economic imbalances, and human psychological biases further amplified these vulnerabilities, transforming a domestic housing issue into a worldwide economic catastrophe. The lessons learned from the GFC have spurred significant reforms in financial regulation, aiming to build a more resilient and transparent financial system, though debates continue on the effectiveness and sufficiency of these changes.
Recommended Further Exploration
- Explore the lasting impacts of the 2008 financial crisis on the global economy.
- Investigate the various government and central bank responses to the Global Financial Crisis.
- Delve into the financial regulatory changes implemented in the wake of the 2008 crisis.
- Understand strategies and policies aimed at preventing future economic crises.