
Navigating K-AUM: Can Trustee-Controlled Assets Be Excluded When Only Advice is Provided?
Unpacking the intricate nuances of K-AUM calculations and the European Banking Authority's perspective on advised assets under trustee control.
Key Insights into K-AUM and Trustee-Controlled Assets
- K-AUM's Core Purpose: K-AUM is a prudential capital requirement designed to capture the risk-to-client associated with an investment firm's management of client assets, emphasizing direct control and discretionary decision-making.
- Distinguishing Management from Advisement: Assets fall under K-AUM if the firm has discretionary portfolio management or non-discretionary arrangements constituting *ongoing investment advice* that implies a level of management responsibility. Pure advisory roles, where the trustee retains full control and execution, typically classify assets as "Assets Under Advisement" (AUA) rather than "Assets Under Management" (AUM), thus potentially excluding them from K-AUM.
- EBA's Principles-Based Approach: While the EBA doesn't have explicit, direct statements on trustee-controlled assets for K-AUM exclusion, their broader guidelines on risk management, own funds, and off-balance sheet items suggest a principles-based approach. This implies that if assets are genuinely non-proprietary and the advising firm has no direct control or management responsibility, exclusion from K-AUM may be justifiable.
Understanding K-AUM: The Bedrock of Investment Firm Capital Requirements
K-AUM, or the Capital Requirement for Assets Under Management, stands as a pivotal K-factor within the European Union's prudential regime for investment firms. Its fundamental purpose is to quantify the risk of harm to clients stemming from the incorrect discretionary management of their assets. This metric is rooted in the value of assets that an investment firm manages for its clients, encompassing both discretionary portfolio management and non-discretionary arrangements that involve ongoing investment advice.
The calculation of K-AUM involves a meticulous process: it's derived from a rolling average of the total monthly assets under management, typically measured on the last business day of each of the previous 15 months, excluding the three most recent monthly values. A coefficient, usually 0.02%, is then applied to this calculated value. This structured approach ensures a consistent and standardized measure of risk exposure across investment firms.
A crucial distinction lies between Assets Under Management (AUM) and Assets Under Advisement (AUA). AUM pertains to assets over which a financial institution exercises direct discretion, including the ability to manage and execute trades. This direct control signifies a higher degree of responsibility and, consequently, a greater risk exposure for the firm. Conversely, AUA refers to assets for which an advisor provides guidance but lacks the direct authority to trade or manage, often due to logistical or regulatory constraints. K-AUM is specifically tied to AUM, meaning the presence of direct management responsibility is paramount for inclusion in its calculation.
The Role of Discretion and Control in K-AUM Calculation
The essence of K-AUM hinges on the concept of 'management' of assets. If an investment firm has full discretion or delegated management, allowing it to make investment decisions and execute trades independently, those assets are unequivocally included in the K-AUM calculation. This direct control signifies that the firm bears the responsibility for the investment outcomes and potential harm to clients, thus warranting a capital requirement.
However, when a firm merely provides advice to a corporate or individual trustee, and the assets remain under the trustee's ultimate control and decision-making authority, the situation becomes more nuanced. In such scenarios, the assets are generally *not* considered "managed" by the advisory firm for K-AUM purposes. The rationale is that the control—and therefore the direct risk exposure—resides with the trustee, not the advising firm. The European Banking Authority (EBA) and other regulatory bodies consistently emphasize that the "management" of assets implies decision-making authority, not just advisory input. This distinction is critical to prevent an underestimation of risk exposure for entities that truly control and manage assets.
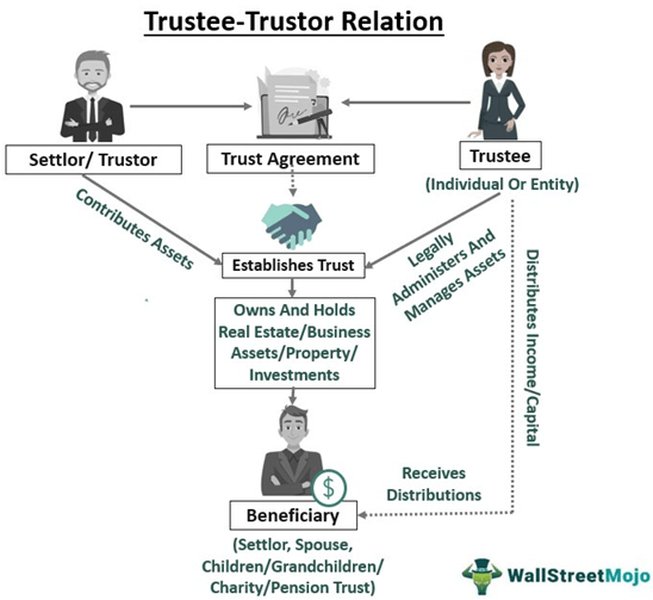
The core relationship between a trustee and a trustor, highlighting asset control.
EBA's Stance on Risk Management and Asset Classification
The European Banking Authority (EBA) plays a crucial role in shaping the regulatory landscape for financial institutions in the EU, issuing guidelines and clarifications on risk management, capital requirements, and prudential standards. While the EBA has not issued a specific, explicit statement directly addressing the exclusion of trustee-controlled assets from K-AUM calculations when only advice is provided, its broader principles and guidelines offer significant insights into how such scenarios might be treated.
Indirect Guidance from EBA Principles
The EBA's focus on robust risk management and accurate assessment of exposures provides a framework for interpreting the treatment of assets under trustee control. Their guidelines often emphasize:
- Non-Proprietary Assets: The EBA's stance, particularly concerning own funds and off-balance sheet items, suggests that assets not directly owned or managed by an advising entity, and therefore not part of its proprietary capital base, might be excluded from its capital calculations. This aligns with the principle that a firm should only hold capital against risks it directly controls or is exposed to.
- Risk Parameter Estimation: EBA guidelines on the estimation of risk parameters (like Probability of Default and Loss Given Default) for various exposures require institutions to classify assets based on their risk profile. If assets under trustee control do not directly impact the advising institution's risk-weighted assets (e.g., they are not on the institution's balance sheet), their exclusion from K-AUM could be justifiable under these principles.
- Governance and Risk Culture: The EBA's emphasis on sound governance and risk culture implies that institutions must have robust arrangements for managing the risks inherent in their business models. This includes carefully assessing which assets truly contribute to their direct risk profile and should therefore be included in capital calculations.
Mermaid.js Mindmap: Key Determinants for K-AUM Exclusion
The following mindmap illustrates the primary factors influencing whether assets under trustee control can be excluded from K-AUM calculations when an advisory firm is involved. It highlights the central role of control and discretion in determining asset classification.
FCA MIFIDPRU and Specific Exclusion Criteria
Beyond the general principles laid out by the EBA, specific regulatory frameworks like the Financial Conduct Authority's (FCA) MIFIDPRU (Markets in Financial Instruments Directive Prudential Requirements) provide more concrete guidance on K-AUM exclusions. MIFIDPRU Rule 4.7.9R outlines limited circumstances under which assets under management may be excluded.
Delegation Versus Advisory-Only Relationships
A key provision in MIFIDPRU allows for the exclusion of assets under management that have been delegated to a firm by a financial entity, provided that the delegating financial entity is already subject to an AUM-based capital requirement similar to K-AUM, or if the FCA has additional supervisory powers over it. This exclusion aims to prevent the double-counting of capital requirements across interconnected financial entities.
However, a crucial caveat exists: this exclusion does *not* apply if the delegating entity (or trustee) only receives advice but maintains control over the assets. The regulatory emphasis remains on whether the investment firm has true discretionary management or delegated authority. If an advisory firm merely provides recommendations without the power to execute trades or make final investment decisions, the assets typically remain under the trustee's control and are not considered part of the advising firm's AUM for K-AUM purposes.
Summary of K-AUM Exclusion Criteria for Delegated Assets
| Condition for Exclusion | Description | Impact on K-AUM |
|---|---|---|
| Delegation by Financial Entity | Assets managed by a firm are delegated from another financial entity that is already subject to an AUM-based capital requirement. | Potential exclusion for the managing firm to avoid double-counting. |
| Part of Same Conglomerate/Group | The delegating financial entity is part of the same financial conglomerate or prudential consolidation group. | Potential exclusion, indicating consolidated oversight. |
| Sub-delegation Limitation | If Firm B excludes assets delegated by Firm A, then Firm C (if Firm B sub-delegates to Firm C) cannot also exclude those sub-delegated assets. | Prevents multi-layered exclusions. |
| Pure Advisory Role (No Delegation) | Advisor provides recommendations, but trustee retains full control, decision-making, and execution authority. | Assets are NOT excluded from the trustee's K-AUM; NOT included in advisor's K-AUM. |
The Nuance of "Assets Under Advisement" (AUA)
The distinction between Assets Under Management (AUM) and Assets Under Advisement (AUA) is fundamental in determining K-AUM applicability. K-AUM is explicitly designed to capture the risk associated with AUM, where the firm has direct control over investment decisions and execution. When advice is provided to a trustee, and the trustee retains all control and discretion over the assets, these assets fall under AUA for the advising firm. This means the firm provides consultative services but does not manage the assets in the regulatory sense required for K-AUM.
For instance, if a corporate or individual trustee holds the legal authority and control over assets in a fiduciary capacity, and only receives investment advice from a third party, the assets remain under the trustee’s control. Consequently, for prudential calculations under the K-AUM requirement, these advised assets cannot be excluded from the trustee’s regulatory capital calculation simply because advice is received. The advice provider does not take on the risk associated with managing those assets directly, so these assets are not reported as managed by the advisor for the purposes of K-AUM.
Evaluating the Impact on Regulatory Risk
The inclusion or exclusion of trustee-controlled assets from K-AUM calculations has significant implications for an investment firm's regulatory risk profile and capital requirements. An accurate assessment ensures that capital adequately reflects the actual risk exposure. The EBA's broader mandate, encompassing areas like credit risk management, operational risk, ICT risk management, and ESG risk management, underscores the importance of a holistic approach to risk assessment. While these areas are distinct from K-AUM, they reinforce the EBA's emphasis on sound governance, comprehensive risk frameworks, and the proper classification of assets and exposures.
The following radar chart illustrates the perceived levels of control and responsibility for different asset scenarios, influencing their potential inclusion in K-AUM calculations. This chart is based on conceptual alignment with regulatory guidelines rather than specific quantitative data.
Implications for Financial Institutions
For investment firms providing advice to trustees, understanding these distinctions is paramount for accurate regulatory reporting and compliance. Misclassifying assets could lead to incorrect capital calculations, potential penalties, and misrepresentation of a firm's true risk profile. While the EBA's direct guidance on this specific scenario might be embedded within broader principles, the consistent message from regulatory bodies is clear: capital requirements are tied to the actual control and management of assets, not merely the provision of advice.
Therefore, firms must undertake a rigorous internal assessment of their advisory relationships with trustees. This includes scrutinizing the terms of engagement to ascertain whether they truly involve delegated management or solely an advisory capacity, where the trustee retains full control. Consulting regulatory texts, such as the full MIFIDPRU handbook and relevant EBA guidelines, and seeking expert legal or regulatory advice, is essential for precise application to specific trustee structures and jurisdictional nuances.
Understanding Trustee-Controlled Assets with a Legal Lens
To further illustrate the context of trustee-controlled assets, here is a helpful video from a legal perspective on how trusts are used to control assets. While not directly about K-AUM, it provides foundational knowledge about the legal framework governing trusts and asset control, which underpins discussions around regulatory capital requirements.
This video explains how trusts are utilized for asset control, a crucial concept when discussing regulatory capital.
This video helps clarify the fundamental principles of trusts and asset control, which are inherently linked to the discussion of K-AUM. When an investment firm advises a trustee, it's operating within this legal framework where the trustee holds significant power and responsibility over the assets. This reinforces why the advising firm's level of control, or lack thereof, is the deciding factor in K-AUM calculations rather than the mere act of providing advice.
Frequently Asked Questions (FAQ)
What is K-AUM?
Can assets under advisement (AUA) be included in K-AUM?
Does the EBA provide specific guidance on trustee-controlled assets and K-AUM?
What is the distinction between delegated management and advisory-only relationships in the context of K-AUM?
What are the implications if assets are incorrectly classified for K-AUM?
Conclusion
In conclusion, when an investment firm provides advice to a corporate or individual trustee, and the assets remain under the trustee's control without any delegation of discretionary management or execution authority to the advising firm, these assets are generally excluded from the advising firm's K-AUM risk calculation. The core principle underpinning K-AUM is the direct control and management responsibility an investment firm has over client assets. If the advising firm's role is purely consultative, classifying the assets as "Assets Under Advisement" (AUA) rather than "Assets Under Management" (AUM), then the capital requirement associated with K-AUM does not apply to those specific assets for the advising firm. While the EBA's clarifications on this specific scenario are primarily derived from its broader principles on risk management, own funds, and off-balance sheet exposures, the consensus from regulatory frameworks like MIFIDPRU reinforces that actual control dictates inclusion in K-AUM. Firms must diligently assess the precise nature of their relationship with trustees to ensure accurate regulatory compliance and appropriate capital allocation.
Recommended Further Exploration
- How is K-AUM calculated under EU Investment Firms Regulation?
- What are the EBA guidelines on risk management for investment firms?
- Differentiate between Assets Under Management and Assets Under Advisement for regulatory purposes.
- What are the FCA MIFIDPRU rules on K-AUM exclusions for delegated assets?